Everyone Loves RWA Stocks Right Now. I Have Questions.

Everyone Loves RWA Stocks Right Now. I Have Questions.

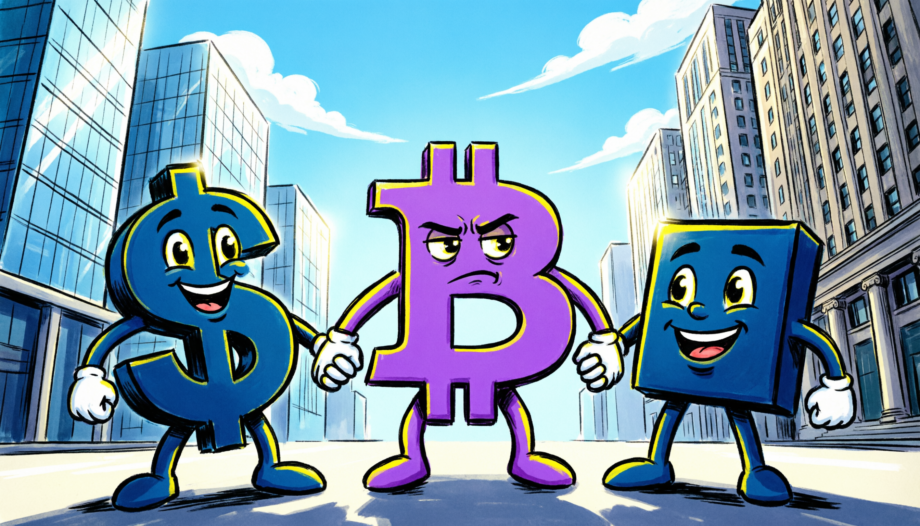
Everyone in the crypto community right now talks about real-world assets as if they’ve found the missing puzzle piece. Digital equity proxies, on-chain corporate shares, and bridge products connecting Wall Street to blockchain wallets dominate the conversation. The narrative feels irresistible. Traditional finance meets decentralized networks, and suddenly your portfolio gains access to prominent technology companies without ever touching a standard brokerage account. I get the excitement. I truly do. But I want to pump the brakes and share a perspective that might ruffle a few feathers. I do not think digital equity wrappers represent a breakthrough for crypto. I also do not think they represent a disaster. They sit in an uncomfortable middle ground, and I believe we need to discuss it honestly.

Let me start with the structural tension that nobody can engineer away. When you buy a blockchain certificate of a public corporation, you do not actually hold that underlying corporate share. You hold a digital receipt that tracks the price of the physical asset. A legal entity, often a special-purpose vehicle, sits between you and the underlying equity. That entity physically custodies the real stock with a traditional broker or bank. So the entire promise of trustless, code-governed finance collapses the moment you need a human institution to safeguard the underlying asset. You trust a company, not a smart contract. And if that custodian faces financial trouble or a legal dispute, your digital receipts could freeze or lose their peg to the real value. The chain breaks at its weakest, most traditional link.

Then there is the ownership question, and it bothers me more than most people admit. Holders of these digital certificates cannot vote in shareholder elections. They cannot attend annual meetings. They do not receive dividends in cash. Instead, the issuing company deducts a 30% US withholding tax from any dividend and reinvests the remainder back into the digital receipt through a supply adjustment. That tax rate comes directly from IRS Chapter 3 rules governing non-U.S. persons receiving U.S.-Source income. Most marketing materials gloss over this detail entirely. You earn less than you expect, and the mechanism feels opaque. I think investors deserve louder, clearer conversations about this reality before they commit capital.

Market depth tells another sobering story. The New York Stock Exchange processes roughly $25 to $30 billion in daily trading volume and relies on thousands of market makers and decades of infrastructure. Compare that figure to the on-chain activity for equity proxies. The entire real-world asset sector, which includes everything from government bonds to private credit to equities, has only recently crossed the $15 billion mark in total value. Within that bucket, the equity slice remains thin. Many digital stock products record sparse weekly transfers after their initial issuance. A handful of platforms boast prominent headline transaction counts, but the number of individual wallets actually holding the certificates remains remarkably small. Try selling a large position on a decentralized exchange, and you will likely encounter wide spreads and heavy slippage. The depth simply does not exist right now.

Compliance hurdles add another layer of friction. These products must comply with securities laws in every jurisdiction they operate in. That requirement means strict identity verification before anyone can mint, redeem, or exchange the assets. Several platforms exclude entire populations, including American citizens and residents, because regulatory agencies leave no practical path forward. So the borderless ideal that drew people to digital networks in the first place quietly disappears behind a compliance wall. You still need approval from a gatekeeper. The gatekeeper just moved to a different server. Operating rhythms also create an awkward mismatch. Public equities trade during set windows, roughly 6.5 hours a day, five days a week, on American exchanges. Blockchain networks run around the clock. When you try to price a digital stock at 3 a.m. on a Sunday, you rely on stale data from Friday’s close. That gap invites confusion and potential manipulation. Not every technological improvement solves a problem that stems from two fundamentally different operating schedules.

Now, I want to be fair. The teams building these products work hard to reduce friction. Some ensure a 1:1 legal backing with real shares rather than synthetic derivatives. Some operate across multiple networks. Some hold regulatory licenses in Europe or the Middle East. Some integrate with decentralized lending protocols, allowing users to borrow against their digital holdings. These efforts deserve recognition. But fixing one problem does not erase the others. The core risk profile stays intact.

If you find yourself in a position where you genuinely cannot access traditional brokerage services and feel you must use these products, I would gently nudge you to keep your certificates on a centralized exchange rather than withdrawing them to a self-custody wallet. Centralized order books absorb large trades with tighter spreads and less slippage. Internal conversions between the digital receipt and the underlying stock position often happen instantly and at zero cost. You can also use those holdings as collateral for derivatives within the same platform. The experience feels closer to what most investors already understand, and the operational risk stays lower.

The decentralized route offers tempting ideas, and I want to acknowledge that fact. You can borrow stablecoins against your stock certificates without selling them. You can bundle digital equities, staking positions, and gold in a single wallet. You can exchange assets at any hour on decentralized aggregators. But smart contract risk looms large with hackers and exploits. Your digital stock could vanish in a single exploit. And thin on-chain market depth means your large sell order could move the price sharply against you. I would rather avoid stacking those risks on top of an already complex structure.

If you have any other path to buy and sell corporate shares through a conventional brokerage, I would take it without hesitation. A regulated broker gives you direct ownership, voting rights, cash dividends, and deep market depth featuring decades of infrastructure. The digital wrapper adds layers of complexity without clearly adding proportional value for the average investor. I do not say any of this to spread fear or undermine the people building in this space. I respect the ambition, and I recognize the genuine effort behind every product. I simply believe the current version of digital equities carries real, unresolved risks that the hype cycle tends to bury. Digital equity proxies avoid disaster. They fail to transform the industry either, at least not right now. They occupy a complicated middle ground, and I think we must discuss that middle ground openly, without cheerleading and without hostility. I may carry my own biases. I acknowledge that freely. But I also think honesty about limitations builds stronger foundations than enthusiasm alone ever could.


Source: https://www.benzinga.com/Opinion/26/08/61389568/everyone-loves-rwa-stocks-right-now-i-have-questions

Anndy Lian is an early blockchain adopter and experienced serial entrepreneur who is known for his work in the government sector. He is a best selling book author- “NFT: From Zero to Hero” and “Blockchain Revolution 2030”.

Currently, he is appointed as the Chief Digital Advisor at Mongolia Productivity Organization, championing national digitization. Prior to his current appointments, he was the Chairman of BigONE Exchange, a global top 30 ranked crypto spot exchange and was also the Advisory Board Member for Hyundai DAC, the blockchain arm of South Korea’s largest car manufacturer Hyundai Motor Group. Lian played a pivotal role as the Blockchain Advisor for Asian Productivity Organisation (APO), an intergovernmental organization committed to improving productivity in the Asia-Pacific region.

An avid supporter of incubating start-ups, Anndy has also been a private investor for the past eight years. With a growth investment mindset, Anndy strategically demonstrates this in the companies he chooses to be involved with. He believes that what he is doing through blockchain technology currently will revolutionise and redefine traditional businesses. He also believes that the blockchain industry has to be “redecentralised”.
j j j

Terraform Labs Founder Do Kwon Will be Extradited to the United States

Terraform Labs Founder Do Kwon Will be Extradited to the United States

According to local reports, Montenegro’s Minister of Justice has signed an order to extradite Terraform Labs founder Do Kwon to the United States, rejecting South Korea’s request for extradition. South Korean authorities accuse Kwon of misleading investors and concealing assets.

This decision follows a Supreme Court ruling in Montenegro, which confirmed that legal requirements for extradition had been satisfied.

Do Kwon To Face Trial in the US

Earlier this week, BeInCrypto reported that a US extradition was likely after Montenegro’s court dismissed Do Kwon’s appeal against extradition, citing legal flaws in his case.

While the extradition date isn’t final yet, Kwon will likely face a trial similar to Sam Bankman-Fried. The FTX founder is currently serving a 25-year sentence, and he was also extradited from the Bahamas. However, his extradition was far less complicated than Kwon’s.

“Taking into account the Supreme Court’s ruling, the Ministry of Justice reviewed all facts and circumstances and assessed criteria such as the severity of the criminal offenses, the location of their commission, the nationality of the requested individual, as well as other circumstances. Based on this, it was concluded that the majority of the criteria stipulated by law favor the request for extradition by the competent authorities of the United States,” stated the Ministry of Justice in its announcement.

The Terraform Labs founder is under investigation in both the US and South Korea for his role in a major cryptocurrency collapse in May 2022.

At that time, the crash of TerraUSD and Luna erased $40 billion from the crypto market. It triggered a widespread financial fallout, leading to the bankruptcy of several companies in the sector.

Furthermore, authorities allege that Kwon deceived investors and suspect he concealed significant assets. In March 2023, Kwon and his business partner, Han Chong Jun, were arrested at Podgorica Airport in Montenegro while attempting to board a flight to Dubai using fake passports.

Kwon was sentenced to four months in prison in Montenegro. However, he is currently detained at the Spuž Centre for Reception of Foreigners.

“Extraditing him to the US could have major implications for how international crypto fraud cases are handled. It’s interesting to see how justice systems across borders interact in these high-profile cases,” author Anndy Lian wrote on X (formerly Twitter).

Historic Settlement with the SEC

In June 2024, Terraform Labs reached a historic settlement with the SEC, agreeing to pay $4.47 billion in penalties. The settlement included $3.6 billion in disgorgement fines, a $420 million civil penalty, and $467 million in pre-judgment interest.

Also, Kwon was personally ordered to pay over $200 million, including $110 million in disgorgement, $80 million in civil penalties, and $14.3 million in interest.

Controversy has also emerged surrounding Kwon’s alleged political connections in Montenegro. Reports suggest he may have financial ties to local political figures, including Milojko Spajic, leader of the Europe Now party.

Overall, these connections raised concerns about potential interference in the extradition process. In 2023, Montenegro’s prime minister called for an investigation into these claims, adding another layer of complexity to the case.


Source: https://beincrypto.com/do-kwon-extradition-us-montenegro/


Anndy Lian is an early blockchain adopter and experienced serial entrepreneur who is known for his work in the government sector. He is a best selling book author- “NFT: From Zero to Hero” and “Blockchain Revolution 2030”.

Currently, he is appointed as the Chief Digital Advisor at Mongolia Productivity Organization, championing national digitization. Prior to his current appointments, he was the Chairman of BigONE Exchange, a global top 30 ranked crypto spot exchange and was also the Advisory Board Member for Hyundai DAC, the blockchain arm of South Korea’s largest car manufacturer Hyundai Motor Group. Lian played a pivotal role as the Blockchain Advisor for Asian Productivity Organisation (APO), an intergovernmental organization committed to improving productivity in the Asia-Pacific region.

An avid supporter of incubating start-ups, Anndy has also been a private investor for the past eight years. With a growth investment mindset, Anndy strategically demonstrates this in the companies he chooses to be involved with. He believes that what he is doing through blockchain technology currently will revolutionise and redefine traditional businesses. He also believes that the blockchain industry has to be “redecentralised”.

j j j

What Singapore should do for Token Regulation: My Suggestions for Proposed DTSPs Framework

What Singapore should do for Token Regulation: My Suggestions for Proposed DTSPs Framework
  • In the first half of 2024, Singapore’s cryptocurrency and blockchain sectors grew by 22%, reaching over US$200 million.
  • The MAS proposed a risk-based regulatory approach to enhance anti-money laundering and counter-financing of terrorism.

Singapore has consistently positioned itself as a forward-thinking jurisdiction, balancing innovation with robust regulatory oversight. As a fellow Singaporean, I am very proud of its future planning.

The Monetary Authority of Singapore (MAS) is seeking submissions for the Consultation Paper on the proposed regulatory approach for Digital Token Service Providers (DTSPs) under the Financial Services and Markets Act 2022.

Instead of replying to the submission directly, I will try to share my point of view openly here, offering insights, potential plans, and timelines for implementation. Before I start, I am sharing this in my personal capacity: I do not represent any self-claimed digital assets expert groups, associations, or schools.

License Application and Fee Structures

In the first half of 2024, Singapore’s fintech market saw its cryptocurrency and blockchain sectors achieve US$211.90 million across 72 deals, marking a 22% increase from US$166.30 million over 38 deals in the second half of 2023.

Singapore has been actively working on strengthening risk management frameworks for digital asset tokenization and has recently launched an initiative to expand asset tokenization within financial services.

The proposed license application processes and fee structures are crucial elements that will shape the DTSP landscape in Singapore. From my perspective, MAS should consider implementing a tiered approach to both timelines and fees, reflecting the diversity of DTSPs in terms of size, complexity, and risk profile.

For timelines, I propose a three-tier system:

Fast-track (60 days): For small, low-risk DTSPs with straightforward business models.

Standard (90 days): For medium-sized DTSPs or those with moderately complex operations.

Extended (120+ days): For large, complex DTSPs or those proposing novel business models.

This tiered approach would allow MAS to allocate resources efficiently while ensuring thorough vetting of more complex applications. The fee structures can follow a similar tiered system based on the DTSP’s annual revenue or transaction volume could be implemented.

Minimum Financial Requirements

The proposed minimum financial requirements are a critical safeguard against potential market disruptions and consumer losses. Based on my analysis, I believe a risk-based approach to setting these requirements is more feasible. This could involve:

Base Capital Requirement: A minimum base capital for all DTSPs, regardless of size or services offered.

Risk-Weighted Capital Requirement: Additional capital requirements based on the DTSP’s types of services offered, transaction volumes, and risk profile.

Liquidity Requirement: A minimum liquidity ratio to ensure DTSPs can meet short-term obligations.

Specifically, providers with capital ratios above 15% were 30% less likely to face operational disruptions during periods of extreme market stress. I propose that MAS consider setting the base capital requirement at SGD 250,000, with additional risk-weighted requirements that could increase this amount up to SGD 5 million for the largest and most complex DTSPs.

Audit Requirements

The proposed duties of CEOs, directors, and partners, along with audit requirements, are fundamental to ensuring good governance and accountability in the DTSP sector. The following enhancement is recommended for consideration:

Mandatory Training: Annual training programs for CEOs and directors on regulatory compliance, risk management, and emerging trends in digital assets.

Risk Committee: DTSPs above a certain size must establish a dedicated risk committee at the board level.

Independent Directors: Mandating a minimum number of independent directors based on the DTSP’s size and complexity.

Audit Frequency: Annual external audits for all DTSPs, with additional quarterly internal audits for larger providers.

Regulators are increasingly leveraging technological solutions to enhance their supervisory functions and manage vast amounts of data. Consequently, firms must engage more frequently with regulators regarding fintech and regtech developments.

Fintech companies that implement robust governance structures and conduct regular audits are indeed less likely to experience compliance breaches.

AML/CFT Measures

The measures proposed in parts 5–8 of the consultation paper, particularly those related to Anti-Money Laundering (AML) and Countering the Financing of Terrorism (CFT), are crucial for maintaining the integrity of Singapore’s financial system. I propose the following enhancements:

Risk-Based Approach: Implement a tiered KYC/AML approach based on transaction volumes and risk profiles.

Technology Integration: Encourage the use of AI and machine learning for transaction monitoring and suspicious activity detection.

Regulatory Technology (RegTech) Sandbox: Establish a sandbox environment for DTSPs to test innovative compliance solutions.

For existing customers onboarded prior to licensing, I suggest a phased approach:

Phase 1 (0–6 months): Risk assessment of existing customer base

Phase 2 (6–12 months): Enhanced due diligence for high-risk customers

Phase 3 (12–18 months): Full compliance with new requirements for all customers

Correspondent Account Services

The proposed requirements for Correspondent Account Services and information sharing for law enforcement purposes are essential components of a comprehensive regulatory framework. Perhaps the following would help:

Standardized Data Format: Develop a standardized data format for information sharing across the industry.

Blockchain Analytics: Encourage the use of blockchain analytics tools to enhance transaction traceability.

Secure Information Sharing Platform: Establish a secure, centralized platform for information sharing between DTSPs and law enforcement agencies.

Blockchain analytics tools have been instrumental in recovering stolen or illicitly obtained digital assets worldwide. They allow law enforcement agencies to trace and identify suspicious cryptocurrency transactions on the blockchain, leading to asset recovery efforts.

Technology Risk Management

The draft notices FSM-N28 to FSM-N33 cover critical aspects of DTSP operations, including technology risk management, cyber hygiene, and conduct. Based on my observations, I propose the following:

Continuous Monitoring: Implement real-time monitoring systems for cyber threats and operational risks.

Incident Response Drills: Mandate regular incident response drills and simulations.

Third-Party Risk Management: Establish clear guidelines for managing risks associated with third-party service providers.

Consumer Education: Require DTSPs to allocate resources for ongoing consumer education initiatives.

Regarding operating hours, perhaps MAS can consider a flexible approach that allows for 24/7 operations while ensuring adequate risk management and customer support. This could involve:

Core operating hours (e.g., 9 AM to 5 PM SGT) with full support services

Extended hours with automated systems and on-call support

Scheduled maintenance windows during low-volume periods

Timeline for Implementation:

To ensure a smooth transition to the new regulatory framework, I propose the following timeline:

Month 0–3: Publication of final regulations and guidelines

Month 3–6: Industry consultation and feedback period

Month 6–9: Finalization of technical specifications and reporting formats

Month 9–12: DTSP preparation and system upgrades

Month 12–18: Phased implementation of new requirements

Month 18–24: Full compliance deadline for all DTSPs

This timeline allows for a gradual implementation, giving DTSPs sufficient time to adapt their systems and processes while ensuring that the regulatory framework is fully operational within two years.

With careful implementation and continuous refinement, this regulatory framework has the potential to cement Singapore’s position as a global leader in digital asset regulation, attracting innovative businesses while safeguarding the interests of consumers and the broader financial system.


Source: https://www.financemagnates.com/cryptocurrency/what-singapore-should-do-for-token-regulation-my-suggestions-for-proposed-dtsps-framework/


Anndy Lian is an early blockchain adopter and experienced serial entrepreneur who is known for his work in the government sector. He is a best selling book author- “NFT: From Zero to Hero” and “Blockchain Revolution 2030”.

Currently, he is appointed as the Chief Digital Advisor at Mongolia Productivity Organization, championing national digitization. Prior to his current appointments, he was the Chairman of BigONE Exchange, a global top 30 ranked crypto spot exchange and was also the Advisory Board Member for Hyundai DAC, the blockchain arm of South Korea’s largest car manufacturer Hyundai Motor Group. Lian played a pivotal role as the Blockchain Advisor for Asian Productivity Organisation (APO), an intergovernmental organization committed to improving productivity in the Asia-Pacific region.

An avid supporter of incubating start-ups, Anndy has also been a private investor for the past eight years. With a growth investment mindset, Anndy strategically demonstrates this in the companies he chooses to be involved with. He believes that what he is doing through blockchain technology currently will revolutionise and redefine traditional businesses. He also believes that the blockchain industry has to be “redecentralised”.
j j j