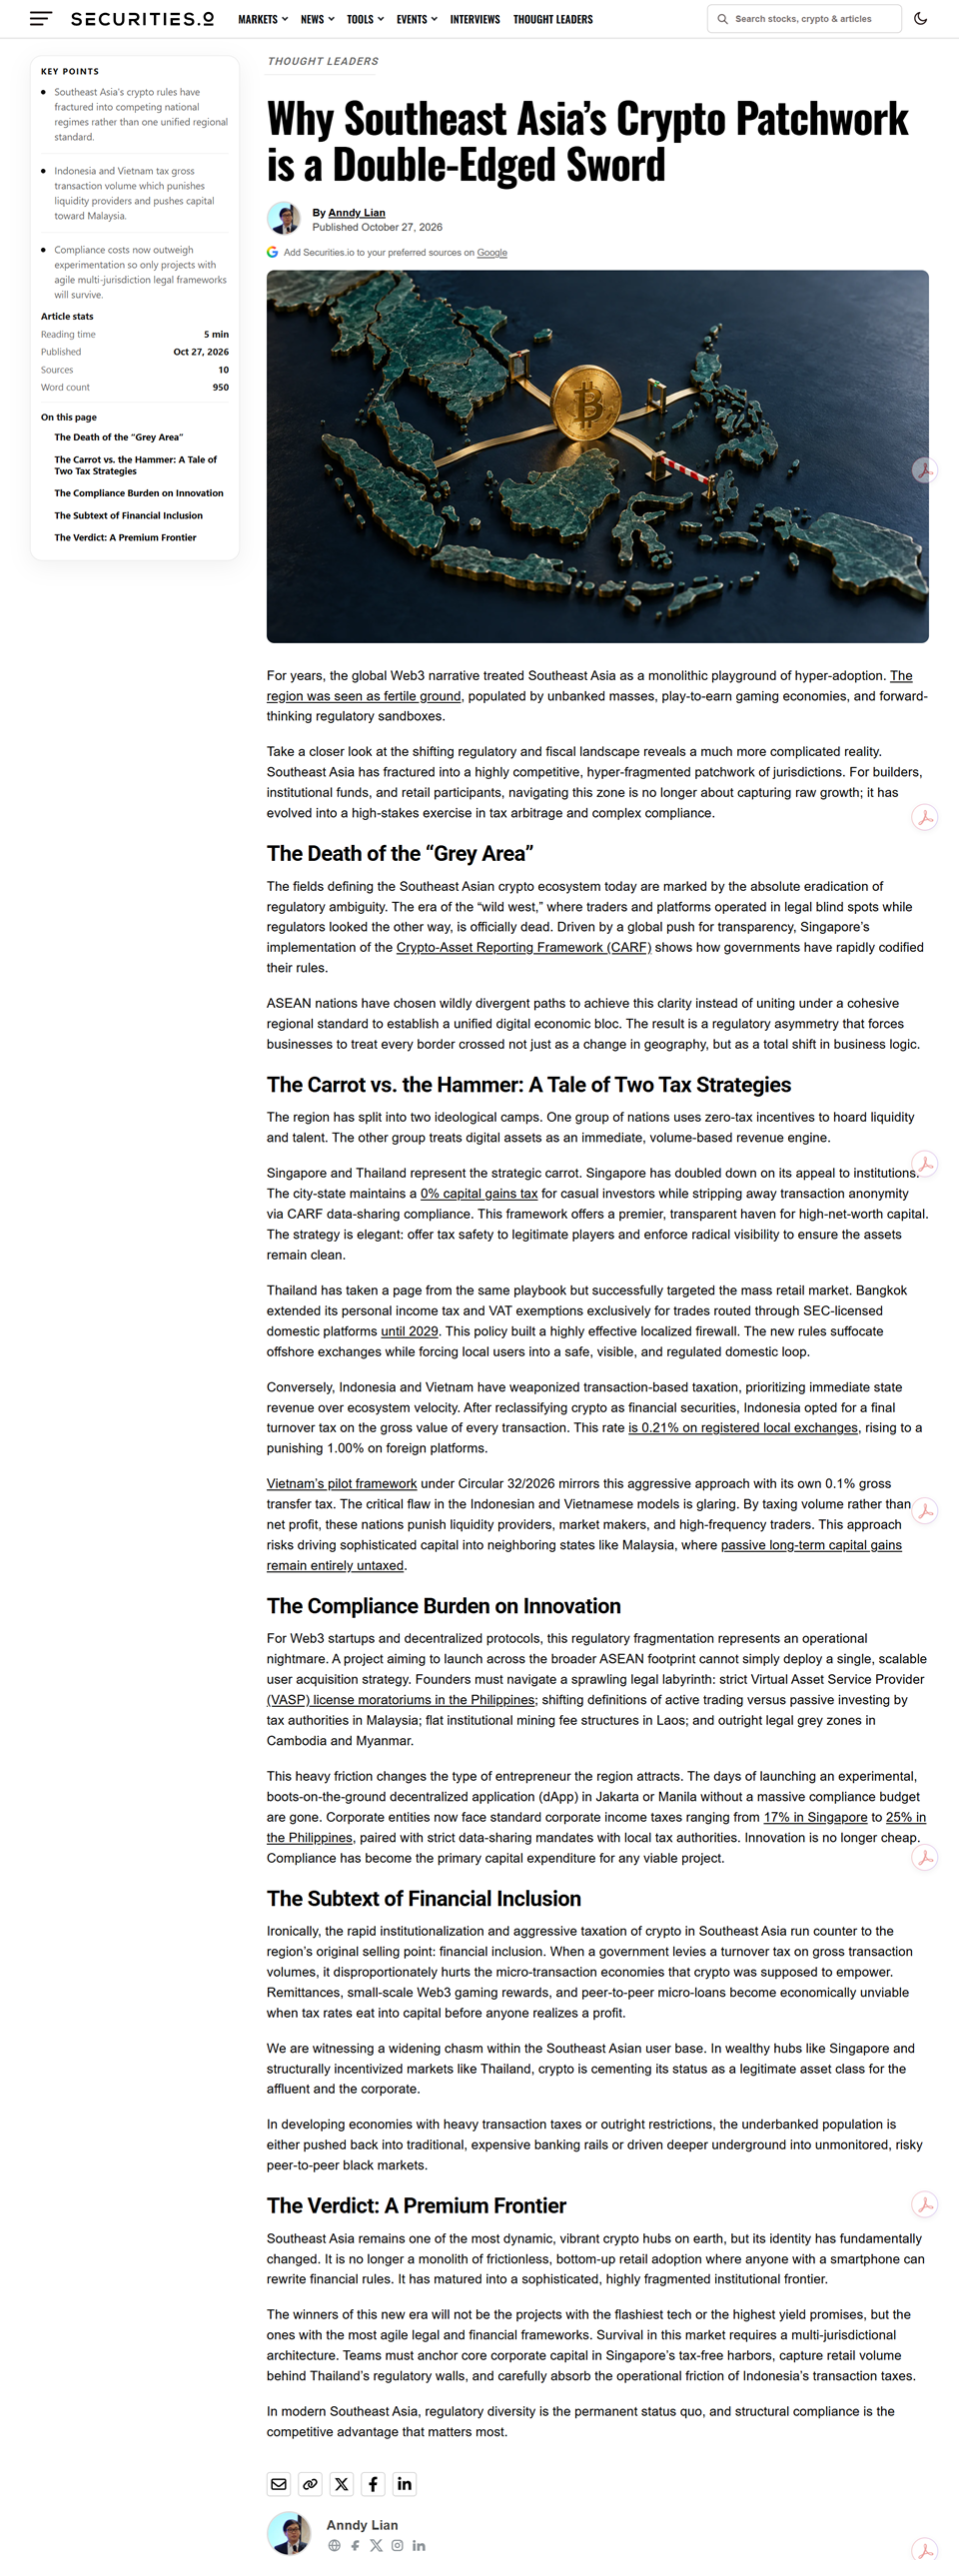
For years, the global Web3 narrative treated Southeast Asia as a monolithic playground of hyper-adoption. The region was seen as fertile ground, populated by unbanked masses, play-to-earn gaming economies, and forward-thinking regulatory sandboxes.
Take a closer look at the shifting regulatory and fiscal landscape reveals a much more complicated reality. Southeast Asia has fractured into a highly competitive, hyper-fragmented patchwork of jurisdictions. For builders, institutional funds, and retail participants, navigating this zone is no longer about capturing raw growth; it has evolved into a high-stakes exercise in tax arbitrage and complex compliance.
The Death of the “Grey Area”
The fields defining the Southeast Asian crypto ecosystem today are marked by the absolute eradication of regulatory ambiguity. The era of the “wild west,” where traders and platforms operated in legal blind spots while regulators looked the other way, is officially dead. Driven by a global push for transparency, Singapore’s implementation of the Crypto-Asset Reporting Framework (CARF) shows how governments have rapidly codified their rules.
ASEAN nations have chosen wildly divergent paths to achieve this clarity instead of uniting under a cohesive regional standard to establish a unified digital economic bloc. The result is a regulatory asymmetry that forces businesses to treat every border crossed not just as a change in geography, but as a total shift in business logic.
The Carrot vs. the Hammer: A Tale of Two Tax Strategies
The region has split into two ideological camps. One group of nations uses zero-tax incentives to hoard liquidity and talent. The other group treats digital assets as an immediate, volume-based revenue engine.
Singapore and Thailand represent the strategic carrot. Singapore has doubled down on its appeal to institutions. The city-state maintains a 0% capital gains tax for casual investors while stripping away transaction anonymity via CARF data-sharing compliance. This framework offers a premier, transparent haven for high-net-worth capital. The strategy is elegant: offer tax safety to legitimate players and enforce radical visibility to ensure the assets remain clean.
Thailand has taken a page from the same playbook but successfully targeted the mass retail market. Bangkok extended its personal income tax and VAT exemptions exclusively for trades routed through SEC-licensed domestic platforms until 2029. This policy built a highly effective localized firewall. The new rules suffocate offshore exchanges while forcing local users into a safe, visible, and regulated domestic loop.
Conversely, Indonesia and Vietnam have weaponized transaction-based taxation, prioritizing immediate state revenue over ecosystem velocity. After reclassifying crypto as financial securities, Indonesia opted for a final turnover tax on the gross value of every transaction. This rate is 0.21% on registered local exchanges, rising to a punishing 1.00% on foreign platforms.
Vietnam’s pilot framework under Circular 32/2026 mirrors this aggressive approach with its own 0.1% gross transfer tax. The critical flaw in the Indonesian and Vietnamese models is glaring. By taxing volume rather than net profit, these nations punish liquidity providers, market makers, and high-frequency traders. This approach risks driving sophisticated capital into neighboring states like Malaysia, where passive long-term capital gains remain entirely untaxed.
The Compliance Burden on Innovation
For Web3 startups and decentralized protocols, this regulatory fragmentation represents an operational nightmare. A project aiming to launch across the broader ASEAN footprint cannot simply deploy a single, scalable user acquisition strategy. Founders must navigate a sprawling legal labyrinth: strict Virtual Asset Service Provider (VASP) license moratoriums in the Philippines; shifting definitions of active trading versus passive investing by tax authorities in Malaysia; flat institutional mining fee structures in Laos; and outright legal grey zones in Cambodia and Myanmar.
This heavy friction changes the type of entrepreneur the region attracts. The days of launching an experimental, boots-on-the-ground decentralized application (dApp) in Jakarta or Manila without a massive compliance budget are gone. Corporate entities now face standard corporate income taxes ranging from 17% in Singapore to 25% in the Philippines, paired with strict data-sharing mandates with local tax authorities. Innovation is no longer cheap. Compliance has become the primary capital expenditure for any viable project.
The Subtext of Financial Inclusion
Ironically, the rapid institutionalization and aggressive taxation of crypto in Southeast Asia run counter to the region’s original selling point: financial inclusion. When a government levies a turnover tax on gross transaction volumes, it disproportionately hurts the micro-transaction economies that crypto was supposed to empower. Remittances, small-scale Web3 gaming rewards, and peer-to-peer micro-loans become economically unviable when tax rates eat into capital before anyone realizes a profit.
We are witnessing a widening chasm within the Southeast Asian user base. In wealthy hubs like Singapore and structurally incentivized markets like Thailand, crypto is cementing its status as a legitimate asset class for the affluent and the corporate.
In developing economies with heavy transaction taxes or outright restrictions, the underbanked population is either pushed back into traditional, expensive banking rails or driven deeper underground into unmonitored, risky peer-to-peer black markets.
The Verdict: A Premium Frontier
Southeast Asia remains one of the most dynamic, vibrant crypto hubs on earth, but its identity has fundamentally changed. It is no longer a monolith of frictionless, bottom-up retail adoption where anyone with a smartphone can rewrite financial rules. It has matured into a sophisticated, highly fragmented institutional frontier.
The winners of this new era will not be the projects with the flashiest tech or the highest yield promises, but the ones with the most agile legal and financial frameworks. Survival in this market requires a multi-jurisdictional architecture. Teams must anchor core corporate capital in Singapore’s tax-free harbors, capture retail volume behind Thailand’s regulatory walls, and carefully absorb the operational friction of Indonesia’s transaction taxes.
In modern Southeast Asia, regulatory diversity is the permanent status quo, and structural compliance is the competitive advantage that matters most.
https://www.securities.io/southeast-asia-crypto-regulation-tax-compliance/
Anndy Lian is an early blockchain adopter and experienced serial entrepreneur who is known for his work in the government sector. He is a best selling book author. The latest book is Web4: The Age of Autonomous Intelligence.


