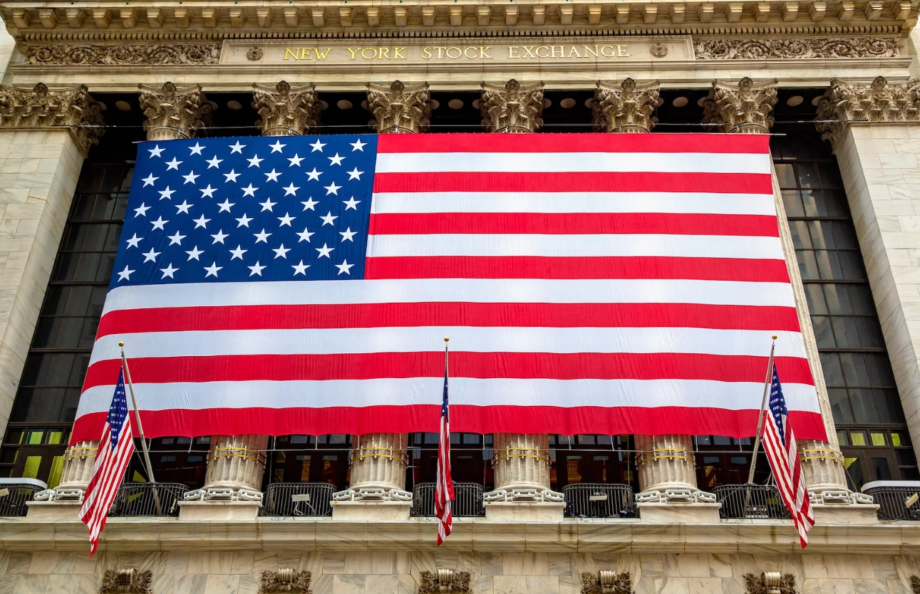
For years, the cryptocurrency industry fought for a seat at the table of traditional finance. Coinbase has finally secured one. On November 6, the Office of the Comptroller of the Currency (OCC) finalized Coinbase’s national trust bank charter, transforming a conditional approval into federal authorization. It is a consequential milestone, placing Coinbase alongside Circle and Ripple in a rapidly expanding group of cryptocurrency companies operating within the federal banking framework.
The obvious narrative is one of triumph: Crypto has finally won the legitimacy it spent years demanding. But the reality is considerably more complicated. Coinbase has acquired significant new opportunities while simultaneously accepting the regulatory constraints that accompany federal oversight. The same charter that opens doors to Wall Street also imposes obligations that could fundamentally reshape how the company does business.
Perhaps the most immediate advantage is regulatory consistency. Until now, Coinbase has operated within a fragmented and expensive landscape of state money transmitter licenses and overlapping regulatory requirements. Federal supervision of its national trust company offers a more unified framework for its authorized trust and custody activities, reducing the uncertainty associated with navigating multiple jurisdictions.
That distinction matters beyond administrative convenience. A federally regulated trust company provides institutional clients with a level of supervisory clarity that a patchwork of state permissions cannot always deliver. For banks, investment managers, and other financial institutions weighing their exposure to digital assets, federal oversight represents an important measure of credibility.
More significantly, the charter positions Coinbase to become part of the institutional infrastructure supporting the next generation of digital finance. Rather than simply serving customers who buy and sell cryptocurrencies, the company can expand its role in safeguarding digital assets and providing services to traditional financial institutions entering the market.
The commercial possibilities extend into stablecoins, digital tokens generally designed to maintain a fixed value against an asset such as the U.S. dollar. Under the framework established by the GENIUS Act, federally regulated institutions and approved issuers have a clearer pathway to providing compliant stablecoin services. Coinbase could capitalize on that environment by offering custody, settlement, and related infrastructure to financial institutions interested in launching or supporting their own digital payment products.
A major Wall Street institution, for example, might eventually rely on Coinbase for parts of the operational infrastructure behind a branded stablecoin rather than developing every custody and compliance function internally. Such arrangements would remain subject to the relevant regulatory approvals and restrictions, but the potential commercial market is substantial.
Coinbase already operates one of the world’s largest cryptocurrency custody businesses. Federal recognition strengthens its position in a market where institutional clients increasingly demand security, regulatory accountability, and operational reliability. The charter also creates opportunities for closer integration with traditional financial infrastructure, although it does not independently guarantee direct access to every conventional banking or payment system.
Yet these advantages come with consequential limitations.
A national trust bank charter is not equivalent to a conventional commercial banking license. Coinbase National Trust Company cannot simply accept ordinary retail deposits, offer FDIC-insured savings accounts, or use customer assets to finance a traditional lending operation. Its business must remain within the activities permitted under its charter and the applicable federal supervisory framework.
The distinction is particularly important when considering stablecoin reserves. Under the GENIUS Act, permitted payment stablecoin issuers face strict requirements governing the assets backing their tokens. These reserves must meet prescribed standards for liquidity, safekeeping, and transparency. The intention is to ensure that stablecoins remain redeemable without exposing holders to the kinds of speculative risks that have repeatedly destabilized parts of the cryptocurrency market.
Where Coinbase acts as a fiduciary or custodian, it must also comply with the legal responsibilities associated with safeguarding assets on behalf of clients. Those obligations constrain how entrusted assets may be managed and prevent the company from treating customer property as an unrestricted source of corporate liquidity.
In effect, Coinbase is exchanging a measure of operational freedom for the credibility of federal supervision. It can seek revenue from custody, technology, and institutional services, but it cannot simply assume the liberties of a lightly regulated cryptocurrency platform while benefiting from the reputation of a federally chartered institution.
This trade-off will shape how the company competes for institutional business. Its national trust charter provides a regulated foundation for custody and related services, but it does not transform Coinbase into a conventional bank capable of lending against customer deposits.
Instead, Coinbase must persuade institutions that its competitive advantage rests on fiduciary discipline, technological sophistication, and the ability to operate securely within a demanding regulatory environment.
That discipline has a cost. Federal examinations, internal controls, reporting obligations, and restrictions on asset management can make financial innovation slower and more expensive. But they also offer the kind of predictability that pension funds, asset managers, and major banks generally demand before committing significant capital or relying on a financial intermediary.
The contrast becomes clearer when Coinbase is compared with Circle and Ripple, two other cryptocurrency companies that have pursued federal trust charters.
Circle has concentrated its strategy on USDC, one of the world’s largest dollar-backed stablecoins. Its federally chartered trust bank is designed to strengthen the oversight and management of the reserves supporting USDC, reinforcing the company’s ambition to become a trusted issuer within the regulated financial system.
For Circle, the principal attraction is credibility in reserve management. Bringing that infrastructure under direct federal oversight could help distinguish USDC from competing stablecoins and reduce some of the regulatory uncertainty surrounding the market.
Ripple has taken a somewhat different approach. Its federally chartered trust bank supports the infrastructure surrounding RLUSD, the company’s dollar-backed stablecoin, including reserve management, collateral trusteeship, and institutional digital asset custody.
Ripple’s broader strategy emphasizes enterprise payments and cross-border settlement. It wants financial institutions to use blockchain technology to move value more efficiently, potentially reducing their dependence on layers of traditional financial intermediation.
Coinbase occupies a different position. Unlike Circle and Ripple, it does not center its business on issuing a proprietary dollar-backed stablecoin. Instead, it aims to provide the infrastructure that other companies need to operate in the digital asset economy.
Its opportunity lies in becoming a trusted custodian, settlement provider, and institutional technology partner for banks and financial companies entering the stablecoin market. If that strategy succeeds, Coinbase could capture substantial business without needing to dominate the issuance of stablecoins itself.
These approaches are not mutually exclusive. Indeed, they illustrate how federal regulation could produce several competing business models within the cryptocurrency industry, each targeting a different part of the financial system.
The next major test arrives on January 18, 2027, when the GENIUS Act and the OCC’s implementing regulations take effect.
The legislation establishes a clearer boundary between stablecoins designed for payments and financial products intended to generate investment returns. In particular, it prohibits payment stablecoin issuers from paying holders interest or yield solely for holding, using, or retaining their tokens.
That restriction addresses a longstanding tension in the stablecoin market. Although these tokens are generally marketed as digital equivalents of cash, some platforms have encouraged their adoption by offering rewards that resemble interest-bearing deposits.
The OCC’s final regulations, however, leave room for a more nuanced interpretation of certain third-party arrangements. The agency removed a proposed presumption that would have treated particular affiliate or third-party payments as potential attempts to evade the yield prohibition.
That decision does not amount to unrestricted permission for exchanges and financial technology companies to pay stablecoin rewards. It does, however, leave such arrangements subject to examination under their specific terms and circumstances rather than an automatic presumption of illegality.
For Coinbase, the distinction is commercially significant.
The company has a longstanding partnership with Circle, under which it receives substantial revenue connected to the distribution and circulation of USDC. The arrangement generally compensates Coinbase for USDC held on its platform while also providing a share of revenue associated with the broader USDC ecosystem, subject to contractual deductions and payments to other approved participants.
These payments are a major part of Coinbase’s stablecoin economics. They also reveal the complexity of introducing a new regulatory framework into an industry whose business relationships developed under considerably different assumptions.
The central question is whether existing revenue-sharing arrangements and customer reward programs will continue to satisfy the GENIUS Act’s restrictions as federal supervision becomes more comprehensive.
Business-to-business revenue sharing is not automatically prohibited simply because it involves income generated by stablecoin reserves. Nevertheless, regulators will be interested in whether particular arrangements effectively channel prohibited yield payments to token holders.
Coinbase therefore faces a delicate balancing act. It must preserve the commercial benefits of its relationship with Circle while ensuring that its activities remain compatible with the federal standards governing stablecoins and fiduciary institutions.
The consequences extend beyond Coinbase. If regulators adopt a restrictive interpretation of indirect stablecoin rewards, exchanges and financial technology companies may need to reconsider how they attract users and monetize stablecoin activity. A more permissive interpretation could preserve important distribution incentives, provided those arrangements do not undermine the law’s prohibition on issuer-paid yield.
Either outcome would influence the economics of an increasingly important segment of digital finance.
Coinbase’s national trust charter is therefore neither an unqualified victory nor a disguised defeat. It represents a calculated exchange of flexibility for institutional legitimacy.
The company has gained a stronger federal foundation for expanding its custody business, serving major financial institutions, and participating in the development of stablecoin infrastructure. In return, it must accept the fiduciary responsibilities, supervisory expectations, and operational restrictions associated with the traditional financial system.
For an industry that spent much of the past decade demanding regulatory clarity, the irony is difficult to miss. Coinbase has finally received the federal recognition it sought, only to discover that legitimacy comes with obligations as well as opportunities.
The question is no longer whether cryptocurrency companies can secure a place within the financial establishment. Coinbase has demonstrated that they can.
The harder question is whether they can preserve the innovation and commercial advantages that made them successful while operating under the rules of the institutions they once hoped to disrupt.
The next year may provide the answer.
https://intpolicydigest.org/coinbase-has-joined-the-banking-establishment-there-s-a-catch/
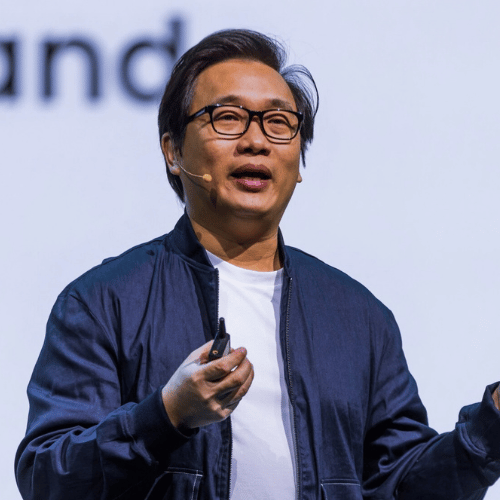
Anndy Lian is an early blockchain adopter and experienced serial entrepreneur who is known for his work in the government sector. He is a best selling book author. The latest book is Web4: The Age of Autonomous Intelligence.