
The memecoin sector often looks like pure chaos to the casual observer, but a strict structural reality exists beneath the surface. Having spent years tracking shifts across digital assets, studying market behaviors, and analyzing on-chain dynamics, I see memecoins not as mindless jokes but as the rawest experiments in market psychology and liquidity distribution. Many market participants assume that every token launch is a lottery ticket governed by pure luck. My perspective is different. When you map long-term cycle patterns directly onto current transaction behavior, the winners share distinct operational markers. Success in this arena is neither accidental nor mystical. It leaves an exact quantifiable footprint across time, volume, and participant velocity.
Consensus in the memecoin space represents the critical threshold where a speculative gamble transforms into an asset anchored by shared belief and broad distribution. Achieving this consensus requires surviving three distinct stages of development, each with clear mathematical guardrails. The entire trajectory hinges on speed and participation. Missing these markers almost always indicates that a token will fade into obscurity, while hitting them creates the foundation for a lasting market presence.
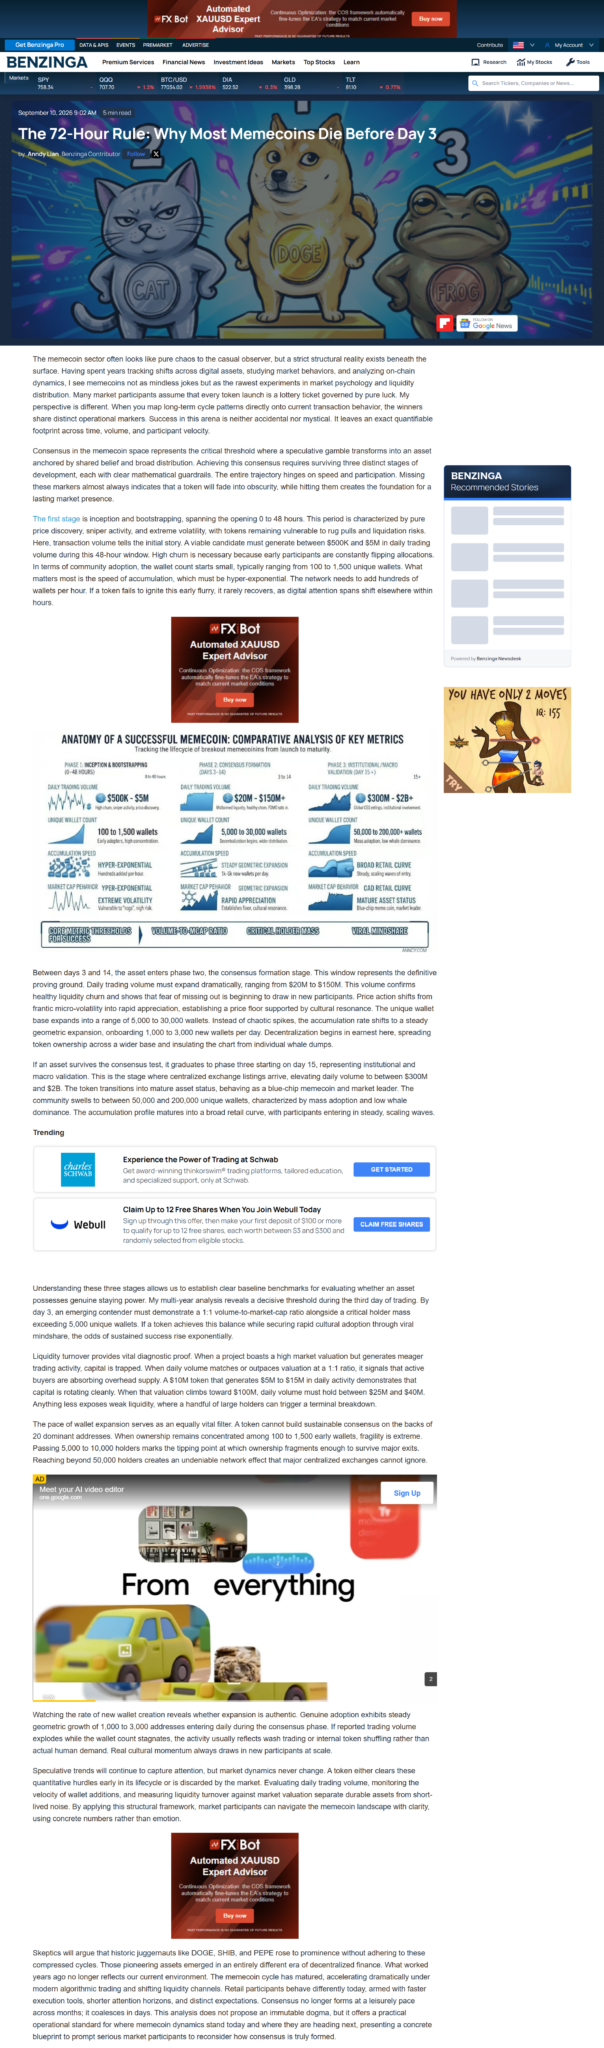
The first stage is inception and bootstrapping, spanning the opening 0 to 48 hours. This period is characterized by pure price discovery, sniper activity, and extreme volatility, with tokens remaining vulnerable to rug pulls and liquidation risks. Here, transaction volume tells the initial story. A viable candidate must generate between $500K and $5M in daily trading volume during this 48-hour window. High churn is necessary because early participants are constantly flipping allocations. In terms of community adoption, the wallet count starts small, typically ranging from 100 to 1,500 unique wallets. What matters most is the speed of accumulation, which must be hyper-exponential. The network needs to add hundreds of wallets per hour. If a token fails to ignite this early flurry, it rarely recovers, as digital attention spans shift elsewhere within hours.
Between days 3 and 14, the asset enters phase two, the consensus formation stage. This window represents the definitive proving ground. Daily trading volume must expand dramatically, ranging from $20M to $150M. This volume confirms healthy liquidity churn and shows that fear of missing out is beginning to draw in new participants. Price action shifts from frantic micro-volatility into rapid appreciation, establishing a price floor supported by cultural resonance. The unique wallet base expands into a range of 5,000 to 30,000 wallets. Instead of chaotic spikes, the accumulation rate shifts to a steady geometric expansion, onboarding 1,000 to 3,000 new wallets per day. Decentralization begins in earnest here, spreading token ownership across a wider base and insulating the chart from individual whale dumps.
If an asset survives the consensus test, it graduates to phase three starting on day 15, representing institutional and macro validation. This is the stage where centralized exchange listings arrive, elevating daily volume to between $300M and $2B. The token transitions into mature asset status, behaving as a blue-chip memecoin and market leader. The community swells to between 50,000 and 200,000 unique wallets, characterized by mass adoption and low whale dominance. The accumulation profile matures into a broad retail curve, with participants entering in steady, scaling waves.
Understanding these three stages allows us to establish clear baseline benchmarks for evaluating whether an asset possesses genuine staying power. My multi-year analysis reveals a decisive threshold during the third day of trading. By day 3, an emerging contender must demonstrate a 1:1 volume-to-market-cap ratio alongside a critical holder mass exceeding 5,000 unique wallets. If a token achieves this balance while securing rapid cultural adoption through viral mindshare, the odds of sustained success rise exponentially.
Liquidity turnover provides vital diagnostic proof. When a project boasts a high market valuation but generates meager trading activity, capital is trapped. When daily volume matches or outpaces valuation at a 1:1 ratio, it signals that active buyers are absorbing overhead supply. A $10M token that generates $5M to $15M in daily activity demonstrates that capital is rotating cleanly. When that valuation climbs toward $100M, daily volume must hold between $25M and $40M. Anything less exposes weak liquidity, where a handful of large holders can trigger a terminal breakdown.
The pace of wallet expansion serves as an equally vital filter. A token cannot build sustainable consensus on the backs of 20 dominant addresses. When ownership remains concentrated among 100 to 1,500 early wallets, fragility is extreme. Passing 5,000 to 10,000 holders marks the tipping point at which ownership fragments enough to survive major exits. Reaching beyond 50,000 holders creates an undeniable network effect that major centralized exchanges cannot ignore.
Watching the rate of new wallet creation reveals whether expansion is authentic. Genuine adoption exhibits steady geometric growth of 1,000 to 3,000 addresses entering daily during the consensus phase. If reported trading volume explodes while the wallet count stagnates, the activity usually reflects wash trading or internal token shuffling rather than actual human demand. Real cultural momentum always draws in new participants at scale.
Speculative trends will continue to capture attention, but market dynamics never change. A token either clears these quantitative hurdles early in its lifecycle or is discarded by the market. Evaluating daily trading volume, monitoring the velocity of wallet additions, and measuring liquidity turnover against market valuation separate durable assets from short-lived noise. By applying this structural framework, market participants can navigate the memecoin landscape with clarity, using concrete numbers rather than emotion.
Skeptics will argue that historic juggernauts like DOGE, SHIB, and PEPE rose to prominence without adhering to these compressed cycles. Those pioneering assets emerged in an entirely different era of decentralized finance. What worked years ago no longer reflects our current environment. The memecoin cycle has matured, accelerating dramatically under modern algorithmic trading and shifting liquidity channels. Retail participants behave differently today, armed with faster execution tools, shorter attention horizons, and distinct expectations. Consensus no longer forms at a leisurely pace across months; it coalesces in days. This analysis does not propose an immutable dogma, but it offers a practical operational standard for where memecoin dynamics stand today and where they are heading next, presenting a concrete blueprint to prompt serious market participants to reconsider how consensus is truly formed.
Source: https://www.benzinga.com/Opinion/26/09/61711802/the-72-hour-rule-why-most-memecoins-die-before-day-3
Anndy Lian is an early blockchain adopter and experienced serial entrepreneur who is known for his work in the government sector. He is a best selling book author. The latest book is Web4: The Age of Autonomous Intelligence.

