92% of Bitcoin Liquidations Were Shorts: What Happens When the Squeeze Ends?

92% of Bitcoin Liquidations Were Shorts: What Happens When the Squeeze Ends?

Bitcoin rose 1.51% to $84,055.22 in 24 hours, and Ethereum rose 0.97% to $2,471.00. The total crypto market cap rose 1.36%. A rebound in technology and AI stock sentiment lifted risk appetite across both assets. Bitcoin showed a 79% correlation with the S&P 500, and its 24-hour correlation with the S&P 500 ETF SPY was 0.79. That shared direction matters. My view is that this rally is real but narrow and derivative-heavy. It supports a cautiously bullish stance, not a conviction breakout call.

The initial driver came from technology and AI sentiment. SpaceX revenue soared 161%, and Super Micro Computer offered positive guidance. Those earnings signals revived broader risk appetite, and that optimism flowed into crypto. Bitcoin’s tight link to the S&P 500 confirms that its short-term direction remains tied to traditional market sentiment, especially around growth and technology narratives. The next test comes from upcoming earnings at major technology firms such as Meta and Tesla. Those reports could sustain the current mood or reverse it. If you have been reading what I wrote recently, I said to treat technology earnings as a near-term macro input, not background noise.

Bitcoin also received a mechanical push from a short squeeze. The asset saw $84.26 million in total liquidations over 24 hours, and shorts made up 92% of that amount. Rising prices forced leveraged short sellers to buy back positions, and that forced buying created a feedback loop that accelerated the upward climb. This matters because derivative market mechanics amplified the rally, not just organic spot demand. That distinction shapes my view. A squeeze can drive a fast climb, but it can also increase volatility and leave the market vulnerable once forced buying runs out. Watch for sustained high funding rates or a sharp contraction in open interest, either of which could signal the squeeze is running out of fuel. This is more tactical rather than structural. A squeeze can pull price toward resistance, and it can also fade once the forced buying stops. I would give more weight to spot demand than to liquidation data when judging whether the rally can last.

On price structure, Bitcoin is testing the upper boundary of a well-defined $80,000 to $87,000 range. The 7-day simple moving average sits near $83,100. If Bitcoin holds above that level and breaks $87,000, it could target $88,000. A rejection could bring a retest of the $80,000 support. The near-term triggers are clear. A daily close above $84,200 would confirm near-term bullish momentum, while a close below $82,000 would signal bearish momentum. The key macro trigger is the Federal Reserve’s rate decision on October 28. Bitcoin is consolidating and awaiting a macro catalyst for its next decisive move. I would want a decisive close above $87,000 after the Fed announcement before treating this as a breakout rather than a range trade. That plan keeps risk defined because the range gives both sides a clear line in the sand. My humble advice is not to chase the climb into $87,000 before the Fed meeting, and I would not treat a single close above $84,200 as proof of a new trend. The central bank decision deserves more weight than 1 session of price action.

Ethereum has its own supply-side catalyst. On October 20 to 21, Tom Lee’s Bitmine staked an additional 159,728 ETH worth approximately $390 million. That brought its total staked holdings to about 5.23 million ETH. This action locks a significant portion of supply, reduces potential sell pressure, and signals strong institutional belief in Ethereum as a yield-generating asset. Large long-term holders are actively choosing to earn yield rather than sell. That provides underlying demand support. The watch point is continued growth in the staking queue, which would indicate sustained demand to lock supply. It gives Ethereum a firmer floor than pure sentiment alone would provide, though a supply lock does not guarantee an immediate breakout.

Ethereum also benefited from the broader market lift. The total crypto market cap rose 1.36%, led by Bitcoin’s 1.51% gain. A rebound in global technology and AI sentiment supported the move, with strong earnings forecasts from companies such as SpaceX helping the mood. Ethereum saw $47.99 million in liquidations over 24h, with shorts comprising the majority. That suggests a squeeze added momentum. Ethereum did not rise alone. It benefited from a risk-on shift in correlated assets. The key watch point is how U.S. equity markets react to upcoming technology earnings from Meta and Tesla, as those reactions can provide continued correlation cues.

Ethereum now faces immediate resistance at the psychological $2,500 level. A sustained break above that level, especially on a daily close, could open the path to the 30-day simple moving average at $2,579. The scheduled activation of Ethereum’s Hoodi testnet upgrade on October 26 could renew developer and investor focus. Failure to hold $2,470 risks a pullback toward the recent low near $2,380. A daily close above $2,500 would confirm bullish momentum, while a drop below $2,380 would signal renewed weakness. My view is that Ethereum needs spot buying volume to accompany a break above $2,500. Without that volume, a rejection would suggest the rally came primarily from derivatives positioning and short covering.

My overall point of view is cautiously bullish on both assets, with a preference for patience over chasing. Bitcoin’s improved risk sentiment and a derivatives squeeze provided a clear catalyst, but the price stayed within a multi-week range and showed little breakout conviction. Ethereum’s substantial supply lock-up and favorable macro backdrop provide a solid floor, but it must break above $2,500 to sustain momentum. The key watch is whether Bitcoin can decisively close above $87,000 after the Fed’s policy announcement and whether Ethereum can break $2,500 with rising spot volume. If those conditions fail, both markets risk reverting to range midpoints or retesting support. The data supports a constructive stance, but not complacency. Macro sentiment and spot demand matter more than a short squeeze, and I’d track those most closely.

My stance leans toward selective exposure rather than aggressive accumulation. The data point to a constructive backdrop, but also to fragile momentum. A trader can respect the range, wait for confirmation, and let the Fed decision and spot volume decide the next leg.


https://e27.co/92-of-bitcoin-liquidations-were-shorts-what-happens-when-the-squeeze-ends-20261022/
Anndy Lian is an early blockchain adopter and experienced serial entrepreneur who is known for his work in the government sector. He is a best selling book author. The latest book is Web4: The Age of Autonomous Intelligence.

j j j

More Holders, Little Trading: The RWA Liquidity Problem Is Worse Than You Think

More Holders, Little Trading: The RWA Liquidity Problem Is Worse Than You Think

Let me ask you something straight. Does real-world asset trading on crypto exchanges feel like a genuine revolution, or does it feel like a warehouse full of boxes nobody opens? I think you know the answer.

The RWA sector has a serious liquidity problem, and saying it out loud shouldn’t make anyone uncomfortable. The numbers tell the story better than any narrative can.

The Scale of the Liquidity Gap

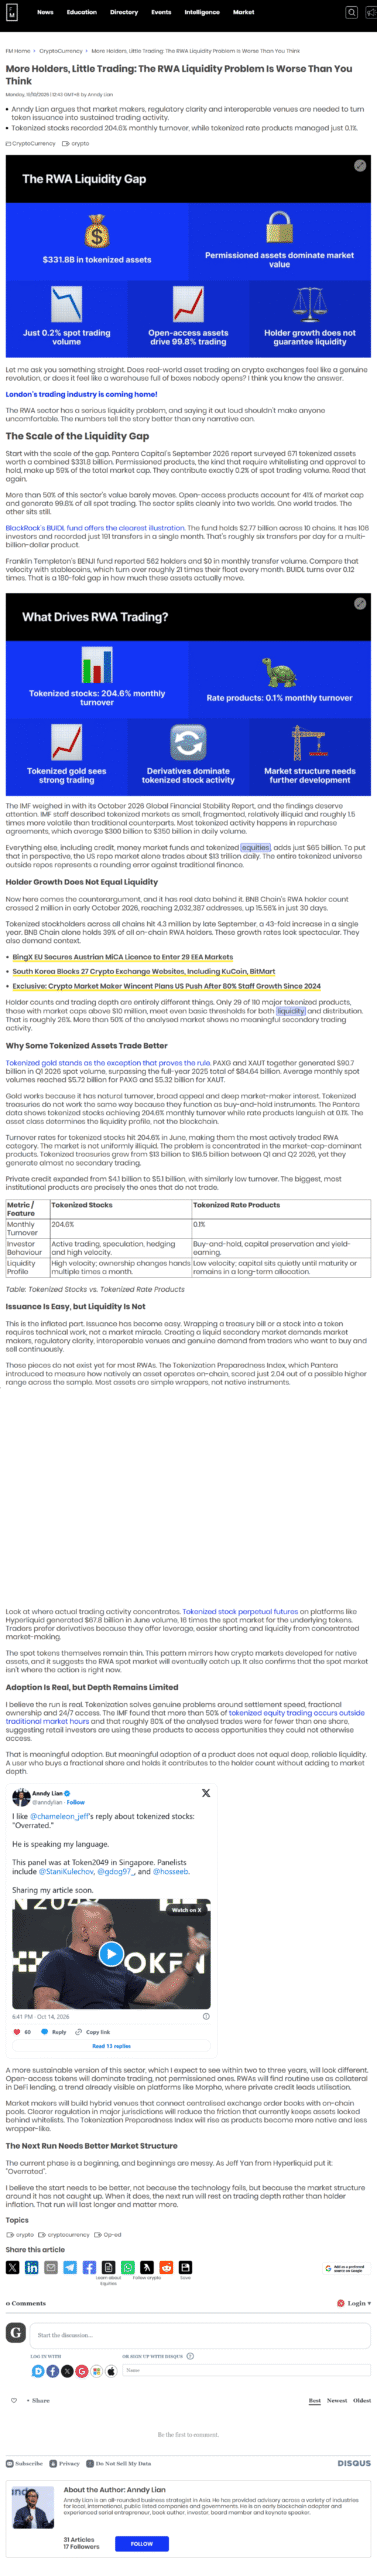
Start with the scale of the gap. Pantera Capital’s September 2026 report surveyed 671 tokenized assets worth a combined $331.8 billion. Permissioned products, the kind that require whitelisting and approval to hold, make up 59% of the total market cap. They contribute exactly 0.2% of spot trading volume. Read that again.

More than 50% of this sector’s value barely moves. Open-access products account for 41% of market cap and generate 99.8% of all spot trading. The sector splits cleanly into two worlds. One world trades. The other sits still.

BlackRock’s BUIDL fund offers the clearest illustration. The fund holds $2.77 billion across 10 chains. It has 106 investors and recorded just 191 transfers in a single month. That’s roughly six transfers per day for a multi-billion-dollar product.

Franklin Templeton’s BENJI fund reported 562 holders and $0 in monthly transfer volume. Compare that velocity with stablecoins, which turn over roughly 21 times their float every month. BUIDL turns over 0.12 times. That is a 180-fold gap in how much these assets actually move.

The IMF weighed in with its October 2026 Global Financial Stability Report, and the findings deserve attention. IMF staff described tokenized markets as small, fragmented, relatively illiquid and roughly 1.5 times more volatile than traditional counterparts. Most tokenized activity happens in repurchase agreements, which average $300 billion to $350 billion in daily volume.

Everything else, including credit, money market funds and tokenized equities, adds just $65 billion. To put that in perspective, the US repo market alone trades about $13 trillion daily. The entire tokenized universe outside repos represents a rounding error against traditional finance.

Holder Growth Does Not Equal Liquidity

Now here comes the counterargument, and it has real data behind it. BNB Chain’s RWA holder count crossed 2 million in early October 2026, reaching 2,032,387 addresses, up 15.56% in just 30 days.

Tokenized stockholders across all chains hit 4.3 million by late September, a 43-fold increase in a single year. BNB Chain alone holds 39% of all on-chain RWA holders. These growth rates look spectacular. They also demand context.

Holder counts and trading depth are entirely different things. Only 29 of 110 major tokenized products, those with market caps above $10 million, meet even basic thresholds for both liquidity and distribution. That is roughly 26%. More than 50% of the analysed market shows no meaningful secondary trading activity.

Why Some Tokenized Assets Trade Better

Tokenized gold stands as the exception that proves the rule. PAXG and XAUT together generated $90.7 billion in Q1 2026 spot volume, surpassing the full-year 2025 total of $84.64 billion. Average monthly spot volumes reached $5.72 billion for PAXG and $5.32 billion for XAUT.

Gold works because it has natural turnover, broad appeal and deep market-maker interest. Tokenized treasuries do not work the same way because they function as buy-and-hold instruments. The Pantera data shows tokenized stocks achieving 204.6% monthly turnover while rate products languish at 0.1%. The asset class determines the liquidity profile, not the blockchain.

Turnover rates for tokenized stocks hit 204.6% in June, making them the most actively traded RWA category. The market is not uniformly illiquid. The problem is concentrated in the market-cap-dominant products. Tokenized treasuries grew from $13 billion to $16.5 billion between Q1 and Q2 2026, yet they generate almost no secondary trading.

Private credit expanded from $4.1 billion to $5.1 billion, with similarly low turnover. The biggest, most institutional products are precisely the ones that do not trade.

Metric / Feature

Tokenized Stocks

Tokenized Rate Products

Monthly Turnover

204.6%

0.1%

Investor Behaviour

Active trading, speculation, hedging and high velocity.

Buy-and-hold, capital preservation and yield-earning.

Liquidity Profile

High velocity; ownership changes hands multiple times a month.

Low velocity; capital sits quietly until maturity or remains in a long-term allocation.

Table: Tokenized Stocks vs. Tokenized Rate Products

Issuance Is Easy, but Liquidity Is Not

This is the inflated part. Issuance has become easy. Wrapping a treasury bill or a stock into a token requires technical work, not a market miracle. Creating a liquid secondary market demands market makers, regulatory clarity, interoperable venues and genuine demand from traders who want to buy and sell continuously.

Those pieces do not exist yet for most RWAs. The Tokenization Preparedness Index, which Pantera introduced to measure how natively an asset operates on-chain, scored just 2.04 out of a possible higher range across the sample. Most assets are simple wrappers, not native instruments.

Look at where actual trading activity concentrates. Tokenized stock perpetual futures on platforms like Hyperliquid generated $67.8 billion in June volume, 16 times the spot market for the underlying tokens. Traders prefer derivatives because they offer leverage, easier shorting and liquidity from concentrated market-making.

The spot tokens themselves remain thin. This pattern mirrors how crypto markets developed for native assets, and it suggests the RWA spot market will eventually catch up. It also confirms that the spot market isn’t where the action is right now.

Adoption Is Real, but Depth Remains Limited

I believe the run is real. Tokenization solves genuine problems around settlement speed, fractional ownership and 24/7 access. The IMF found that more than 50% of tokenized equity trading occurs outside traditional market hours and that roughly 80% of the analysed trades were for fewer than one share, suggesting retail investors are using these products to access opportunities they could not otherwise access.

That is meaningful adoption. But meaningful adoption of a product does not equal deep, reliable liquidity. A user who buys a fractional share and holds it contributes to the holder count without adding to market depth.

A more sustainable version of this sector, which I expect to see within two to three years, will look different. Open-access tokens will dominate trading, not permissioned ones. RWAs will find routine use as collateral in DeFi lending, a trend already visible on platforms like Morpho, where private credit leads utilisation.

Market makers will build hybrid venues that connect centralised exchange order books with on-chain pools. Clearer regulation in major jurisdictions will reduce the friction that currently keeps assets locked behind whitelists. The Tokenization Preparedness Index will rise as products become more native and less wrapper-like.

The Next Run Needs Better Market Structure

The current phase is a beginning, and beginnings are messy. As Jeff Yan from Hyperliquid put it: “Overrated”.

I believe the start needs to be better, not because the technology fails, but because the market structure around it has not caught up. When it does, the next run will rest on trading depth rather than holder inflation. That run will last longer and matter more.


Anndy Lian is an early blockchain adopter and experienced serial entrepreneur who is known for his work in the government sector. He is a best selling book author. The latest book is Web4: The Age of Autonomous Intelligence.

j j j

Bitcoin’s $82,000 Bounce: Did Trump’s Iran Pledge Stop the Bleed?

Bitcoin’s $82,000 Bounce: Did Trump’s Iran Pledge Stop the Bleed?
The past few days have shown Bitcoin traders how quickly macro forces can flip the script. A sharp selloff driven by fears of a wider conflict in the Middle East found a sudden reprieve when Donald Trump pledged not to launch new strikes on Iran before the upcoming US midterm elections. Trump described talks as productive. That statement rippled through energy and bond markets, giving risk assets, including Bitcoin, room to breathe.

My view is that this episode reveals something important about Bitcoin’s current market structure. The cryptocurrency has become highly sensitive to geopolitical and broad economic crosscurrents, perhaps more so than many long-term holders would like to admit. The drop from near $87,000 to around $80,400 was not due to anything intrinsic to Bitcoin itself. It came from oil price spikes and surging bond yields, which forced large macro funds to reduce risk across the board. When Trump’s pledge eased those pressures, Bitcoin bounced back toward the low $82,000s, touching around $82,600 in early trading. That recovery was real, but it was also shallow and fragile.

Consider the oil and bond dynamics more carefully. Reuters reported that Brent crude fell to about $102 and WTI to around $90 following Trump’s comments. China’s refined-fuel exports also weighed on prices, helping ease inflation concerns. On the bond side, US Treasury yields had hit multi-decade highs earlier in the week. After the pledge, 10-year yields hovered near 5.24% rather than surging further. Lower oil and steadier yields reduce the immediate incentive for macro funds to sell risk assets. That makes it easier for Bitcoin to stabilize, but it does not create a durable floor on its own.

What stands out is the shift in positioning that accompanied the rebound. Before the pledge, Bitcoin had suffered over $1 billion in long liquidations amid Iran-linked oil worries and ETF outflows. After the statement, the pressure shifted onto shorts as price rebounded. CoinDesk noted that the pledge underpins crypto gains and that bears faced liquidation pressure. Another outlet highlighted BTC reclaiming above $82,000 while stressing that timing alone does not prove causation. I find that caution appropriate. The correlation is clear, but proving that Trump’s statement directly caused the bounce is impossible. What we can say is that easing Iran fears lined up with the recovery and a rotation of liquidations from longs to shorts.

That distinction matters because a rebound that relies on short covering can fade quickly once those positions are cleared. A rebound that relies on fresh spot demand tends to last longer. The current move looks more like the former than the latter. Traders should also note that ETF outflows over 2 sessions show institutional buyers have not rushed back in. Without that support, the market relies on derivatives and short-term flows, which can reverse fast.

The lesson for traders is that Bitcoin no longer trades in isolation. When oil and yields move, crypto follows. Trump’s pledge bought time, but it did not change the underlying structure. A market that depends on short covering and modest funding will struggle to sustain gains without spot demand. That is why I keep coming back to ETF flows and total market cap as the real tests of whether this bounce can last.

Still, the underlying demand picture remains weak. Spot Bitcoin ETFs saw net outflows in the hundreds of millions over 2 sessions. The total crypto market cap rose only about 0.2% over 24 hours, with Bitcoin dominance near 59.4%. Those numbers tell a story of stabilization rather than a strong new impulse higher. If real demand were returning, I would expect to see ETF flows turn positive and total market cap expand more meaningfully. Instead, we see a market that stopped bleeding but has not found a clear reason to rally.

The derivatives picture adds another layer of nuance. Open interest has fallen over the week, and funding is only modestly positive. That indicates some leverage has washed out, which is healthy in the short term. It also means leverage has not disappeared entirely. Both squeeze risk and downside air pockets remain in play. If oil spikes again or yields resume their climb, the same macro funds that reduced risk before could do so again, and Bitcoin would likely face renewed selling pressure.

Looking ahead, I see 3 key variables that will determine whether this is a durable floor or just a pause. The first is geopolitics. Trump’s pledge is time-bound and contingent. Renewed strikes or shipping disruptions in the Gulf could drive oil back up and re-ignite risk-off selling. The second is macro and flows. Watch oil, 10-year yields, and spot BTC ETF flows. A return of heavy outflows or a renewed spike in yields would weaken the case that the selloff has ended. The third is positioning. If open interest rebuilds and funding turns strongly positive, that would suggest traders are leaning long again, which could set up another squeeze if macro conditions deteriorate.

My overall assessment is that the easing of the selloff is as much about reduced geopolitical stress and a leverage reset as it is about new demand. Trump’s Iran pledge removed 1 immediate tail risk, helping oil and yields cool. That gave Bitcoin room to recover from an over-leveraged, macro-driven pullback. The recovery lacks conviction. ETF outflows continue, total market cap gains are minimal, and the geopolitical situation remains fluid. I would treat this as a pause rather than a trend shift until ETF flows turn positive and oil and yields stay contained for longer.

Confidence in this view is moderate. Multiple independent reports document the pledge, the oil and bond moves, and the Bitcoin rebound. The causal link between the statement and price action cannot be fully proven. What is clear is that Bitcoin remains tightly tied to macro forces beyond its control. For traders, that means watching oil, yields, and ETF flows as closely as they watch on-chain data or technical levels. For long-term holders, it means accepting that geopolitical headlines can still drive significant short-term volatility.

The coming days will tell us whether this is a genuine floor or just a temporary reprieve. If Middle East tensions remain contained and ETF outflows slow, Bitcoin could consolidate rather than cascade lower. Any renewed shock in oil or yields can quickly revive selling pressure. The market has bought itself some time. Whether it uses that time to build a base or simply waits for the next macro shoe to drop is the real question.


Source: https://coinmarketcap.com/community/articles/6ac9da8d1f531212d224a5dd/


Anndy Lian is an early blockchain adopter and experienced serial entrepreneur who is known for his work in the government sector. He is a best selling book author. The latest book is Web4: The Age of Autonomous Intelligence.
j j j