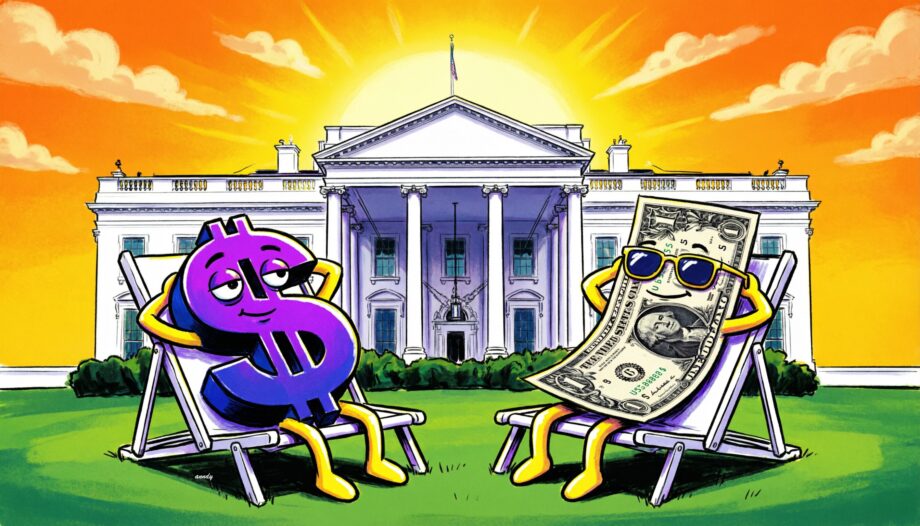
CLARITY Act Dies—Stablecoin Yields Survive

CLARITY Act Dies—Stablecoin Yields Survive

The CLARITY Act died on the Senate floor this week. A procedural vote failed 49 to 50, short of the 60 needed to move forward. Senator Cynthia Lummis, the bill’s most passionate advocate, called it over. For anyone who spent the past year hoping Congress would finally deliver a comprehensive rulebook for digital assets, the result stings.

But here is the thing about Washington. When 1 door slams shut, another often stays cracked open. For stablecoin holders, that crack is wide enough to keep earning yield.

Changpeng Zhao, the former Binance chief, pointed out the silver lining shortly after the vote failed. His take was simple. The technology keeps moving. The yield keeps flowing. If there is any silver lining, stablecoins can continue to have yield, CZ wrote. The CLARITY Act would have added new restrictions on stablecoin rewards. It did not pass. Those restrictions never took effect.

Let me walk through what this means, because the details matter more than the headlines.

The CLARITY Act was a big bill. It aimed to divide oversight of crypto between the SEC and the CFTC. It tackled decentralized finance. It created a circuit breaker mechanism that would have let the Treasury Department restrict stablecoin rewards for up to 18 months if those rewards threatened to pull deposits out of community banks with less than $10 billion in assets. Banking groups loved that provision. Crypto exchanges hated it.

The bill failed. Those proposed limits on platform-level stablecoin rewards vanished with it.

Now, here is the part people often miss. Stablecoins already operate under a separate law called the GENIUS Act, which Congress passed and President Trump signed in July 2025. That law bars stablecoin issuers from paying interest or yield directly to token holders. GENIUS Act Section 4(a)(11) bans stablecoin issuers from paying holders any yield. Circle cannot pay you interest on your USDC. Tether cannot pay you interest on your USDT. That restriction remains in force today.

But the GENIUS Act never restricted platforms. Exchanges, wallets, and other intermediaries can still pay rewards on stablecoin balances they hold for customers. The GENIUS Act permits intermediaries such as exchanges to pass yield from the underlying Treasury reserves to users. DeFi protocols can still generate returns through lending, liquidity provision, and other on-chain activity.

This is not a technicality. It is the core of how stablecoin yield works in practice.

Take Coinbase. The exchange pays USDC holders 3.5% APY on balances held in its app. Coinbase calls this a loyalty reward. The money comes from a revenue-sharing arrangement with Circle, the company that issues USDC. Coinbase does not issue USDC. Circle does. Coinbase pays USDC holders 3.5% APY, calls the payment a loyalty reward, and books the residual under a 50/50 revenue share of reserve income with Circle.

That arrangement sits outside the GENIUS Act’s issuer yield ban. The statute bans issuer-paid yield. It does not ban affiliate-paid yield. Issuer-paid yield was banned. Affiliate-paid yield was not addressed. The reward Coinbase pays sits structurally outside the statute as enacted.

The numbers here are substantial. Coinbase reported $305 million in Q1 2026 stablecoin revenue, the single largest line inside a subscription and services business that now contributes 44% of total revenue. The platform holds more than a quarter of all USDC in circulation, roughly $19 billion in balances inside its products.

DeFi protocols offer another channel. Aave, the largest decentralized lending protocol with approximately $38.6 billion in TVL, pays USDT supply rates typically between 4% and 6% APY. On Aave, USDC supply rates typically track USDT closely at 4% to 6% APY, with Compound offering USDC yields in the 4% to 7% APY range. Morpho Blue adds a premium of 50 to 150 basis points over Aave for equivalent risk. Ethena’s sUSDe has paid between 5% and 15% historically, though those yields fluctuate with market conditions.

These returns come from real economic activity. Borrowers pay interest. Traders pay funding rates. Liquidity providers earn fees. The yield is not a marketing gimmick. It reflects actual demand for capital.

The stablecoin market itself has grown enormously. Total stablecoin market cap reached roughly $316 billion as of June 12, 2026, according to DefiLlama data. That is nearly 12 times the $27 billion recorded at the end of 2020. USDT holds about 59% of supply and USDC about 24%, a combined 83% of the market. Citigroup projects the market could reach $1.9 trillion by 2030. Standard Chartered sees $2 trillion by the end of 2028.

Those projections assume stablecoins keep offering competitive yields. If regulators kill yield entirely, the math changes. The banking industry knows this. That is why the American Bankers Association and 7 other trade groups fought so hard for the CLARITY Act’s yield restrictions. The American Bankers Association and others have urged lawmakers to use the Clarity Act to close a legal loophole that allows digital asset service providers to avoid the existing prohibition on stablecoin interest and yield.

Their argument is straightforward. If stablecoins pay attractive yields, depositors will move money out of traditional bank accounts and into stablecoin platforms. Community banks will lose funding for loans. Small businesses will suffer. The state associations said stablecoins should serve as a payment tool, not a store of value. They warn that such incentives could move deposits away from local lenders.

The crypto industry calls that argument anticompetitive. Banks pay interest on deposits. Why should stablecoin platforms face a different standard?

History offers an interesting parallel. In 1980, the Independent Bankers Association warned that money market funds would drain deposits and weaken lending. A letter submitted by the Independent Bankers Association of America in a 1980 hearing of the Senate Banking Committee on money market funds made arguments almost verbatim from what they argue today: threat to deposits, harms lending, uniquely dangerous for smaller banks. Money market balances grew parabolically into the trillions, and banks remain flush with deposits. Bank deposits did not disappear. By 2022, Federal Reserve data put total bank deposits near $18 trillion.

The CLARITY Act’s failure does not settle this debate. It simply delays it.

The Office of the Comptroller of the Currency has proposed a rule that would treat certain issuer-platform revenue-sharing arrangements as a workaround of the GENIUS Act ban. The notice of proposed rulemaking issued on February 25, 2026 includes a rebuttable presumption that any coordinated arrangement between an issuer and an affiliate or related third party to pay holders yield is itself a prohibited yield arrangement. The comment period closed on May 1, 2026. Banks pushed for an even broader reading. Exchanges pushed back hard.

If the OCC’s reading survives, the Coinbase-Circle rewards structure could face serious challenges. That would hurt Coinbase’s revenue. It would also hurt Circle, which relies on Coinbase as its largest distribution partner. In 2024, Circle paid Coinbase $908 million of its $1.01 billion in total distribution costs. That payment exceeded Circle’s net income. Circle’s net profit was $155 million in 2024.

But as of today, that rule remains a proposal. It has not taken effect. The yield continues.

My point is not that regulation does not matter. It was that technology does not wait for politicians. Stablecoin yield exists because people want it. Borrowers want capital. Lenders want returns. Exchanges want revenue. Users want passive income on their digital assets.

The CLARITY Act would have added a layer of restrictions on top of the GENIUS Act. It failed. That layer never materialized. Platforms can still pay rewards. DeFi protocols can still generate yield. The market keeps functioning.

This is not a permanent state of affairs. Future legislation could change the rules. The OCC could finalize its proposed rule. Enforcement actions could shift the landscape. But for now, the situation is clear. The extra platform-level ban did not become law. Stablecoin yield continues through existing channels.

For anyone holding stablecoins and wondering whether they can still earn a return, the answer is yes. The CLARITY Act failed. Everything continues. And that is worth noting, even if the broader regulatory picture remains frustratingly incomplete.


Source: https://www.benzinga.com/Opinion/26/09/61816221/clarity-act-dies-stablecoin-yields-survive
Anndy Lian is an early blockchain adopter and experienced serial entrepreneur who is known for his work in the government sector. He is a best selling book author. The latest book is Web4: The Age of Autonomous Intelligence.

j j j

Bitcoin just rallied on regulation: Why the CLARITY Act changes everything

Bitcoin just rallied on regulation: Why the CLARITY Act changes everything
Bitcoin climbed 2.45 per cent to US$81,511.13 over the last 24 hours, outpacing the broader digital asset market’s 1.97 per cent gain. This move did not happen in isolation. A decisive regulatory breakthrough in Washington provided the spark, while crowded derivative positioning added fuel.

The correlation between Bitcoin and the S&P 500 now sits at 0.91, signalling that macro forces and policy shifts drive price action as much as any blockchain metric. This moment looks like an inflection point where regulatory clarity finally begins to align with market reality, creating conditions for sustainable institutional participation without sacrificing the core principles of decentralisation.

The passage of the CLARITY Act through the US Senate Banking Committee represents the most tangible progress the industry has seen in years. The committee approved H.R. 3633 in a 15-9 vote on May 14, 2026, moving the bill toward a full Senate floor vote, where prediction markets currently assign a 73 per cent probability of passage. This legislation resolves two persistent friction points that have hampered US innovation.

First, it establishes a workable framework for stablecoin rewards. Crypto firms can now offer activity-based incentives to users who transact, trade, spend, or stake their tokens, while prohibiting purely passive interest payments that traditional banks argued resembled deposit-taking. This compromise acknowledges that digital assets operate on different economic primitives than legacy finance.

Second, the Act draws a clear jurisdictional boundary between the CFTC and SEC. Most mainstream tokens now fall under the CFTC’s commodity oversight, while only a narrow subset retains security classification. This ends the era of regulation by enforcement and gives builders the predictability they need to deploy capital with confidence.

Market structure amplified the regulatory catalyst. Derivatives data shows total open interest surged 37.14 per cent in 24 hours, while Bitcoin’s funding rate turned deeply negative just before the rally. This setup created a crowded short position, making it vulnerable to a squeeze. When the price began moving higher on the CLARITY Act news, forced buying from short covering accelerated the move. Liquidation data confirms this dynamic, with US$71.02 million in short bets wiped out over the same period.

This leverage-driven volatility is a feature, not a bug, of maturing markets. It reflects growing participation from sophisticated traders who understand how to position around policy events. Even so, it also means that sharp moves can extend in either direction. Sustained high open interest suggests continued volatility as the market digests this new regulatory landscape.

From a technical perspective, Bitcoin now tests a critical confluence zone. The 200-day simple moving average sits near US$82,000, at US$82,455. A confirmed daily close above this threshold, especially with the CLARITY Act advancing toward a full Senate vote, opens a path toward the Fibonacci extension target at US$85,102. The immediate support band ranges from US$80,000 to US$80,458.

Holding this zone keeps the bullish structure intact. Conversely, a break below US$78,000 would invalidate the near-term uptrend and risk triggering approximately US$1 billion in long liquidations, potentially pushing the price toward US$70,000. These levels reflect collective market psychology and liquidity pools rather than arbitrary lines. The current setup favours bulls, but only if they can defend recent gains against profit-taking and macro headwinds.

The broader macro backdrop adds another layer of complexity. Global equity markets show mixed signals as an AI-driven rally pauses. The S&P 500 recently closed above 7,500 for the first time, while the Dow Jones recaptured 50,000 on strong corporate earnings.

US equity futures now trend 0.1 per cent to 0.2 per cent lower as investors assess geopolitical risks. The Trump-Xi summit in Beijing commands attention, while tensions in the Strait of Hormuz keep energy markets on edge. Brent crude climbed 0.9 per cent to hover above US$106 per barrel, marking a five per cent weekly gain due to the blocked shipping lane. These inflationary pressures feed into Treasury yields, with the 10-year note advancing to 4.51 per cent and the two-year settling near 4.04 per cent.

The Bloomberg Dollar Spot Index strengthened 0.1 per cent, pressuring gold, which fell 0.6 per cent to US$4,619 per ounce. In this environment, Bitcoin’s 0.91 correlation with the S&P 500 suggests it will likely continue to move in lockstep with risk assets until a distinct crypto-native catalyst emerges. The CLARITY Act may provide that catalyst, but only if it clears the full Senate without material dilution.

This regulatory progress matters most for what it enables next. Clear rules allow institutions to allocate capital with defined compliance pathways. They let builders focus on product innovation rather than legal defence. And they give retail participants greater confidence that the platforms they use operate within a stable framework.

Anndy Lian is an early blockchain adopter and experienced serial entrepreneur who is known for his work in the government sector. He is a best selling book author. The latest book is Web4: The Age of Autonomous Intelligence.

j j j

The truth behind the CLARITY Act lobby blitz: Crypto to the moon or banks compromise

The truth behind the CLARITY Act lobby blitz: Crypto to the moon or banks compromise

The digital asset market currently reflects a complex tapestry of legislative hope and aggressive capital rotation. Total market valuation climbed 2.08 per cent in just 24 hours, reaching US$2.74T. This move aligns closely with traditional finance, as evidenced by an 87 per cent 30-day correlation with the S&P 500 index. While many observers look to pure technical indicators, the underlying strength stems from a growing belief that the CLARITY Act will finally establish a federal framework for the industry.

This optimism acts as a tailwind for prices even as a shadow looms in the form of a last-minute offensive from the traditional banking sector. The current rally suggests that participants are beginning to price in the possibility of a regulated future, even as the establishment fights to maintain its grip on dollar deposits and payment flows.

Capital is clearly searching for higher returns beyond the established giants. The Altcoin Season Index jumped 4.26 per cent in 24 hours and 22.5 per cent over the week to reach a level of 49. This indicates a significant shift in trader behaviour, as capital flows into higher-beta assets with specific growth stories. Sui serves as a prime example of this trend, as its price surged by over 24 per cent. A Nasdaq-listed firm decided to stake 108.7M tokens, which represents 2.7 per cent of the total supply.

This move created an immediate supply shock by removing millions of tokens from the active sell side. Combined with the announcement that African fintech giant Paga would integrate with the Sui network, the asset demonstrated that targeted adoption news now outweighs general market movements. Traders are no longer just buying the broad market. They are hunting for specific catalysts and supply dynamics that can deliver outsized gains.

Bitcoin itself continues to hold the line at US$82,139.04, marking a 1.83 per cent increase that tracks the broader market cap rise of 1.88 per cent. Trading volume for the leading asset spiked by 48.97 per cent. This confirms that the break above the US$82,000 psychological level has weight and attracts both retail and institutional participation. Data from derivatives markets suggests that leverage played a heavy hand in this climb. Open interest for Bitcoin futures surged past the previous all-time high set in 2025.

This influx of leveraged positions triggered a classic short squeeze, with short liquidations totaling US$23.93M in 24 hours. This represents a 16.67 per cent increase over the previous period. When short sellers face forced buybacks, they inadvertently push prices higher, creating a cascade of upward pressure. This feedback loop benefits spot holders but also increases the risk of a sudden reversal if the market becomes overextended on borrowed capital.

Market indicators provide a nuanced view of this momentum. Data highlights that while the 14-day Relative Strength Index sits at 68.43, it has not yet hit the extreme levels that typically signal an immediate crash. Bitcoin dominance holds steady near 60.15 per cent. This suggests that the rally has not yet fully rotated capital into smaller tokens, despite gains in the altcoin sector. Social sentiment remains bullish with a net score of 5.21 out of 10.

Traders consistently highlight profitable trades in the altcoin market. Total open interest across all assets rose 6.07 per cent to reach US$451.72B. This shows that new money is entering the derivatives space to bet on further gains. These bets amplify price moves and ensure that volatility remains a constant companion for those navigating these markets.

The regulatory landscape remains the most potent driver for long-term sentiment and institutional trust. The CLARITY Act represents a rare moment of bipartisan cooperation between Senators Thom Tillis and Angela Alsobrooks. Their hard-won compromise focuses on a critical distinction for stablecoins. It prohibits passive, deposit-style interest but allows rewards tied to actual usage, transactions, or liquidity provision.

This framework would allow the industry to flourish while theoretically protecting consumers from the risks associated with unregulated shadow banking. Prediction markets like Polymarket now place the odds of passage at 75 per cent. Public support appears robust, with a HarrisX poll showing 52 per cent of voters favour the move. This legislation aims to reshore digital asset activity to American venues. Such a move could potentially end the dominance of offshore issuers like Tether and bring innovation back to domestic soil.

Traditional financial organisations are not watching these developments with indifference or passivity. Just 4 days before the May 14 Senate Banking Committee markup, powerful trade groups, including the American Bankers Association and the Bank Policy Institute, launched a concerted effort to derail the yield compromise. These organisations sent a joint letter urging senators to scrap the rewards carve-out entirely.

While they publicly cite consumer protection concerns, their internal analysis reveals a deeper fear about their own profit margins. These banks warn that yield-bearing stablecoins could drain enough liquidity from the traditional system to reduce consumer, small-business, and farm lending by 20 per cent or more. This battle is essentially a struggle for control over the future of dollar deposits and the rails of the global payments system.

The outcome of this markup will determine whether non-bank issuers retain the room they need for innovation or whether the United States remains with its current fragmented regime.

Timing is now the greatest risk for the pro-crypto camp and the broader market structure. If the Senate Banking Committee advances the bill without reopening the fight over yields, a July 4 signing target at the White House remains a realistic possibility. If the banking lobby successfully delays the markup beyond the May 21 Memorial Day recess, the entire effort could reset and lose its momentum.

Policy experts warn that missing this window could delay the development of clear rules until a new Congress takes office in the coming years. This uncertainty explains why social sentiment remains cautiously bullish at 5.21 out of 10. Traders are celebrating recent gains but remain wary of the political hurdles that lie ahead. The market is at an inflection point, where the durability of the current rotation hinges on whether leadership can maintain momentum amid institutional pushback from legacy finance.

Investors should recognise that this rally is not just a random price fluctuation. It is a reaction to a specific legislative shift that threatens the traditional banking monopoly. The push by banks to strip stablecoin rewards from the CLARITY Act proves that they see digital assets as a legitimate threat to their lending models and deposit bases. If the act passes in its current form, it will validate the point of view that clear rules and usage-based rewards are the true catalysts for the next phase of growth.

For now, the market is betting that the senators will hold their ground against the banking lobby. If they succeed, the shift of capital from Bitcoin into select altcoins with strong narratives will likely continue. If they fail, the industry may have to wait much longer for the clarity it needs to fully integrate with the global financial system and move away from its offshore roots.

The clash between the crypto market and the banking sector is reaching a boiling point. This is healthy for the end user, as it drives innovation and offers more choices about where and how to hold value. The coming weeks will reveal whether the legislative process can withstand the pressure from established interests or yield to the status quo. If the current momentum holds, we are witnessing the birth of a new era in digital finance.


Anndy Lian is an early blockchain adopter and experienced serial entrepreneur who is known for his work in the government sector. He is a best selling book author. The latest book is Web4: The Age of Autonomous Intelligence.

j j j