Macro reality check: Why US$4,000 gold and falling BTC go hand in hand

Macro reality check: Why US$4,000 gold and falling BTC go hand in hand

Risk sentiment has retreated sharply, not due to a sudden economic contraction, but rather to growing investor unease over the sustainability of surging artificial intelligence-related capital expenditures and a surprisingly hawkish pivot from the US Federal Reserve.

Despite delivering a widely anticipated 25-basis-point rate cut to a target range of 3.75 per cent to 4.00 per cent, Chair Jerome Powell used the post-decision press conference to push back firmly against expectations of further easing, warning that inflation remains sticky and that the labour market, while cooling, still shows signs of underlying strength. This messaging effectively neutralised the dovish implications of the cut itself, triggering a repricing across asset classes.

Equity markets responded with a clear rotation out of high-duration tech names. The Nasdaq fell 1.6 per cent, significantly underperforming the Dow Jones, which declined only 0.2 per cent. This divergence underscores a market increasingly sceptical of the lofty valuations underpinning the AI trade, which had been a primary driver of the year’s gains. The repricing was mirrored in the bond market, where yields edged higher.

The benchmark 10-year Treasury yield climbed by two basis points to settle at 4.097 per cent, while the two-year yield rose one basis point to 3.608 per cent. This steepening of the yield curve, albeit modest, signals that traders are now pricing in a more prolonged period of elevated rates than previously expected. The US Dollar Index capitalised on this shift in sentiment, rising 0.3 per cent to 99.53, its highest level in three months, as global capital sought the relative safety of the greenback.

This risk-off environment spilt over into commodities and, more acutely, into the cryptocurrency market. Gold, often a haven during uncertainty, surged by 2.4 per cent to close at an extraordinary US$4,023.20 per ounce, a level that speaks to deep-seated anxieties about long-term monetary debasement and a potential flight from traditional financial assets. In the oil market, Brent crude was relatively stable, gaining just 0.1 per cent to settle at US$65 per barrel.

This calm, however, belies a complex backdrop. The market is digesting news that OPEC+ is poised to approve another modest output increase of 137,000 barrels per day for December, a move that would continue its gradual unwinding of production cuts. This potential supply boost is being counterbalanced by new US sanctions on Russia, which have stoked uncertainty about the reliability of global oil supply, creating a tense equilibrium that has so far prevented a major price move in either direction.

Against this macroeconomic tapestry, the cryptocurrency market has entered a period of pronounced weakness. Over the past 24 hours, the total market capitalisation has fallen by two per cent, extending a monthly decline of 6.46 per cent. The current market cap stands at approximately US$3.67 trillion, a figure that has broken below both its seven-day and 30-day simple moving averages, signalling a clear deterioration in its technical structure. This downturn is not a simple market correction but the result of a confluence of powerful, bearish forces operating in unison.

The most significant driver of this weakness is a sudden and substantial exodus of institutional capital from Bitcoin spot ETFs. On October 30, these funds recorded a net outflow of US$488 million, the largest single-day withdrawal since June 2025. The selling was led by the market’s two heaviest weights: BlackRock’s IBIT saw US$291 million flee its coffers, while Ark Invest’s ARKB bled a further US$65.6 million. This synchronised institutional retreat is a critical development.

For much of 2025, the steady inflow of capital into these ETFs had been the bedrock of Bitcoin’s price stability and its primary source of new demand. The abrupt reversal suggests that large, sophisticated players are either taking profits after a strong run or, more ominously, are repositioning their portfolios in anticipation of a more challenging macro environment ahead. With total ETF assets now at US$143.9 billion, the market is now on high alert for November’s flow data, which will be the key indicator of whether this is a temporary pause or the beginning of a sustained institutional withdrawal.

Compounding this problem is a sharp contraction in the derivatives market. Total open interest, a measure of the total value of outstanding leveraged bets, has plummeted by 4.4 per cent, falling from US$848 billion to US$812 billion. At the same time, average funding rates on perpetual futures contracts have turned negative, settling at -0.0018 per cent. This combination is a classic sign of market deleveraging.

Traders are actively closing their long positions, often at a loss, to reduce their risk exposure. While this process of forced liquidation removes the immediate threat of a cascading crash, it also strips the market of its bullish momentum. The negative funding rate confirms that the short-term sentiment is firmly bearish, as those holding short positions are now being paid to do so by the longs who remain in the market.

From a technical perspective, the picture is equally grim. The market has not only broken key moving averages but has also seen its Relative Strength Index (RSI) fall to 40.9, entering oversold territory. The Moving Average Convergence Divergence (MACD) indicator remains in negative territory, suggesting that the bearish momentum is still in control.

This creates a precarious situation where the market is technically primed for a bounce, but the underlying trend remains firmly down. The next major support level appears to be the US$3.6 trillion mark, a 78.6 per cent Fibonacci retracement level, which will be a critical test of the market’s resilience.

The prevailing sentiment is one of fear. The market’s Fear and Greed Index has plunged to 31, a level categorised as Extreme Fear and the lowest it has been in a week. This psychological state is further amplified by a rising Bitcoin dominance index, which now sits at 59.3 per cent.

When Bitcoin’s share of the total crypto market cap increases during a downturn, it typically indicates that investors are fleeing from riskier altcoins and rotating into what they perceive as the safest asset in the space. This dynamic suggests that if the current pressure continues, altcoins could face even more severe selling than Bitcoin itself.

In conclusion, the crypto market’s current malaise is a direct reflection of a broader macroeconomic shift. The trifecta of institutional caution, derivatives deleveraging, and a broken technical structure has created a formidable headwind. While the oversold conditions may eventually attract bargain hunters, the market is in desperate need of a catalyst to reverse its course.

That catalyst could come in the form of a renewed wave of ETF inflows, signaling that institutions have regained their confidence, or from a more dovish signal from the Federal Reserve that eases the pressure on risk assets. Until then, the path of least resistance remains lower, and all eyes will be on whether Bitcoin can hold its October low near US$105,000 as the ultimate test of its underlying support.

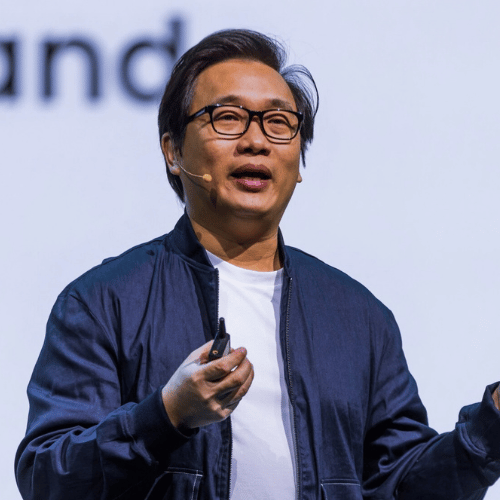


Anndy Lian is an early blockchain adopter and experienced serial entrepreneur who is known for his work in the government sector. He is a best selling book author. The latest book is Web4: The Age of Autonomous Intelligence.
j j j

S&P 500 eyes 7000, gold at US$4113, Bitcoin breaks US$115K: Here’s what’s driving the surge

S&P 500 eyes 7000, gold at US$4113, Bitcoin breaks US$115K: Here’s what’s driving the surge

The S&P 500, currently trading in the high 6700s as of late October 2025, hovers just below the psychologically significant 7000 threshold. A credible and durable US-China trade agreement could propel the index toward that level by year-end, a move representing a 2.8 per cent upside from current levels.

Such optimism remains contingent on tangible outcomes rather than mere rhetoric. The market’s advance hinges not only on macro diplomacy but also on the micro-level performance of 177 companies reporting earnings this week. Only consistent beat-and-raise guidance, where firms exceed earnings expectations and raise forward-looking forecasts, will sustain the fragile momentum. Without such confirmation, the rally risks unravelling under the weight of its own narrow breadth and elevated leverage.

Gold continues to serve as a strategic hedge amid rising macro uncertainty. Technical analysis points to structured accumulation zones at 3700 dollars and 3500 dollars, levels that have repeatedly attracted institutional and algorithmic buying. Despite an environment of loose monetary conditions and accelerating inflation expectations, correlated at plus 28 per cent with M2 money supply growth, portfolio allocations to gold remain strikingly low.

Only 2.4 per cent of fund managers hold more than five per cent of their assets in gold, suggesting significant room for reallocation if inflation proves persistent or if geopolitical tensions escalate. The metal’s recent consolidation near US$4113 per ounce reflects this tension between fundamental tailwinds and tepid institutional demand, a divergence that often precedes sharp re-pricing.

China’s evolving economic strategy adds another layer of complexity. The 15th Five-Year Plan for 2026 to 2030 formally pivots away from the old growth model centred on property and infrastructure toward human capital development and domestic consumption. This shift is more than semantic. The term consumption appears four times in the latest Communist Party Plenum Communiqué, compared to just once in 2020, signalling a deliberate policy recalibration.

Property, once the engine of Chinese growth, remains under regulatory scrutiny and is unlikely to receive meaningful stimulus, especially as exports continue to outperform. Instead, Beijing prioritises technological self-reliance and innovation, aiming for a sustainable 4.5 per cent annual growth rate through productivity gains rather than debt-fuelled asset bubbles. For global investors, this transition implies that Chinese equities may offer value but with heightened volatility tied to policy execution and external trade dynamics.

The US equity market, in contrast, has become increasingly concentrated. Performance is now effectively a binary bet on the success of artificial intelligence monetization within the MAG7 cohort, those mega-cap tech firms generating multi-billion-dollar free cash flows. Public AI plays appear safer than their private counterparts, like OpenAI or Anthropic, which remain unprofitable and lack a clear killer app to justify their valuations.

Even among public firms, the path to AI-driven revenue remains elusive. This narrow leadership amplifies systemic risk, particularly as leveraged ETFs magnify both upside and downside moves. A barbell strategy, pairing large-cap growth exposure with high-dividend yield stocks, remains prudent, especially when considering Japan’s continued commitment to Abenomics 3.0 under Prime Minister Takaichi, which supports regional diversification.

This week’s volatility triggers are unusually dense. Beyond the FOMC decision and Big Tech earnings, markets must navigate Donald Trump’s visit to Asia, Jensen Huang’s keynote at a major AI conference, and most critically, the Trump-Xi bilateral meeting on October 30 during the APEC summit in South Korea. Early signals suggest progress.

Chinese officials report a preliminary consensus on export controls, fentanyl trafficking, and maritime levies. These incremental steps have already fuelled a cross-asset rally, with Asian equities up 1.5 per cent and US index futures pricing in a 0.6 per cent gap-up at the open. Copper and Brent crude have surged on improved global growth expectations, while the US Dollar Index holds steady at 98.95, reflecting balanced risk sentiment.

The crypto market has surged in tandem, rising 3.62 per cent in 24 hours and 5.91 per cent over the week. This move stems from three reinforcing narratives. First, macro liquidity expectations have intensified as US bank reserves at the Federal Reserve declined to 2.93 trillion dollars, the lowest level since early January, and what analysts like Adam Livingston describe as nearing a danger zone. Historically, such reserve contractions in 2019, 2020, and 2023 preceded Fed interventions and sharp Bitcoin rallies. Markets now price in a 96.7 per cent probability of a 25-basis-point rate cut at the October 28 to 29 FOMC meeting, reinforcing the liquidity pivot thesis.

Second, institutional demand is accelerating. South Korea’s Bitplanet has initiated daily Bitcoin purchases targeting 10,000 BTC, following Metaplanet’s earlier treasury move of 25,555 BTC. Simultaneously, US spot Bitcoin ETFs recorded over 600 million dollars in net inflows last week, drawing approximately 62,000 BTC from exchange cold storage and tightening supply dynamics. This absorption of available supply reduces float and increases scarcity, particularly as Bitcoin dominance dips slightly to 58.84 per cent, indicating capital rotation into altcoins like Ethereum, which gained six per cent against BTC.

Third, technical momentum has ignited a leverage reset. Bitcoin’s breakout above 115,000 dollars, a level confirmed by multiple sources, triggered 350 million dollars in short liquidations, forcing leveraged bears to cover positions rapidly. Open interest in derivatives markets has climbed 6.95 per cent to 903 billion dollars, reflecting renewed speculative activity. However, funding rates have spiked by 105 per cent in 24 hours, and the RSI sits at a neutral 47.49, suggesting the rally may pause for consolidation rather than accelerate further immediately.

In summary, today’s market environment reflects a delicate balance between hope and reality. Macro optimism, fueled by potential US-China détente and anticipated Fed easing, has aligned with institutional crypto accumulation and technical breakouts to drive risk assets higher. The sustainability of this move depends on concrete outcomes: a credible trade deal, consistent earnings beats, and actual monetary policy accommodation.

If the Fed under-delivers or corporate guidance falters, the leveraged nature of current positioning could trigger a sharp reversal. Investors should monitor Bitcoin’s 113,500 dollar support and Ethereum’s 4,000 dollar level as near-term barometers of sentiment. The week ahead will not merely test market resilience. It will define the narrative for the final quarter of 2025.


Source: https://e27.co/sp-500-eyes-7000-gold-at-us4113-bitcoin-breaks-us115k-heres-whats-driving-the-surge-20251027/

Anndy Lian is an early blockchain adopter and experienced serial entrepreneur who is known for his work in the government sector. He is a best selling book author. The latest book is Web4: The Age of Autonomous Intelligence.

j j j

Gold at record highs, crypto on a knife’s edge: Contradictions in a risk-on world

Gold at record highs, crypto on a knife’s edge: Contradictions in a risk-on world

I see broad optimism coexists with deep structural vulnerabilities. At the heart of this dynamic lies the S&P 500, which remains technically constructive despite recent volatility. However, this strength is not evenly distributed. The rally is overwhelmingly concentrated in a narrow cohort of AI-linked equities, with AI-related stocks now accounting for 43 per cent of the index’s total market capitalisation.

This level of concentration creates a precarious foundation, as the overall health of the market hinges on the performance of a select few firms. Investors are increasingly discerning, favouring publicly listed companies with proven profitability over private, unprofitable ventures that promise future AI breakthroughs but lack current earnings.

This shift reflects a maturing of the AI investment thesis, where the market demands tangible monetisation rather than speculative potential. The upcoming 2026 earnings cycle will serve as a critical stress test, as these AI leaders must demonstrate a clear and scalable path to converting their technological edge into sustained revenue and profit growth.

This selective bullishness unfolds against a backdrop of a supportive macroeconomic environment. The 10-year US Treasury yield has recently dipped to 3.98 per cent, a level that signals a market expectation of a dovish Federal Reserve trajectory. Investors are now pricing in up to five rate cuts by September 2026, which would bring the Federal Funds Rate down to 2.75 per cent.

This anticipated monetary easing acts as a powerful tailwind for risk assets, providing a safety net that encourages investors to stay engaged in the market. Compounding this effect is the favourable seasonal trend that typically characterises the year-end period, creating a setup that is historically conducive to positive returns. Investor sentiment remains a study in contradictions.

While a significant 60 per cent of fund managers believe equities are overvalued, they are simultaneously positioned as “nervous longs,” maintaining high exposure to emerging markets, the highest level since February 2021. This barbelled strategy, which pairs long equity positions with investments in stable, high-yield sectors like telecoms and healthcare while simultaneously shorting the US dollar, reveals a deep-seated caution. Within this cautious framework, the utilities sector stands out as a “boring but brilliant” opportunity, with analysts anticipating double-digit earnings growth in the third quarter of 2025, offering a haven of predictable returns in an otherwise speculative market.

A key barometer of this fragile confidence is the price of gold, which has reached a record high of US$4,356.30 per ounce. This surge is primarily driven by persistent central bank buying, a trend that has been a cornerstone of the gold bull market that began in 2001. Historical analysis of that previous decade-long run suggests the current cycle may only be at its midpoint, providing a long-term bullish narrative.

However, the recent steepness of the price trajectory has raised alarms, as sharp corrections often follow such rapid ascents. The metal now sits at a critical crossroads, with its future path dependent on external geopolitical and political factors. A de-escalation of global tensions or a swift resolution to the US government shutdown would remove key drivers of safe-haven demand, posing a significant downside risk to the gold price.

The immediate catalyst for the latest market moves was a wave of positive quarterly earnings that alleviated fears about the health of the regional banking sector, thereby reviving global risk appetite. A significant policy development in Japan further amplified this positive sentiment. The Financial Services Agency has proposed a landmark reform that would allow domestic banks to buy, hold, trade, and custody Bitcoin and other digital assets, treating them similarly to traditional securities like stocks and government bonds.

This move is a seismic shift for a nation that has been a cautious but steady participant in the crypto space. Major institutions like Mitsubishi UFJ are already developing stablecoins, and this regulatory green light would create a powerful, regulated on-ramp for Japan’s over 12 million crypto account holders, channeling institutional capital directly into the market. This development was the primary driver behind the recent gains in Bitcoin and BNB, which are seen as the most direct proxies for institutional adoption.

The crypto market’s 0.78 per cent rise over the last 24 hours, however, tells a more complex story than just a bullish regulatory headline. The surge in perpetuals trading volume by 65.85 per cent to US$1.56 trillion, coupled with a 6.88 per cent decline in open interest, paints a picture of a market in flux. This data suggests that traders are actively closing out their highly leveraged positions in the wake of last week’s US$16 billion in liquidations, and are now cautiously re-entering the market with new, more conservative bets.

This is further confirmed by the sharp 152 per cent increase in funding rates over the past day, indicating a return of speculative interest, albeit a more measured one. From a technical perspective, the market found a crucial support level at the US$3.6 trillion market capitalisation mark, which corresponds to the 78.6 per cent Fibonacci retracement of its recent uptrend.

With the RSI-14 indicator exiting oversold territory at 33.21, many traders viewed the preceding seven-day, six per cent selloff as a prime buying opportunity. However, the lack of a broad-based rally, evidenced by a weak Altcoin Season Index of just 26, shows that this optimism is largely confined to the largest, most established cryptocurrencies.

In conclusion, the markets are navigating a delicate balance. The powerful, narrow rally in AI stocks and the supportive macro outlook provide a strong foundation, but the extreme concentration of risk and cautious investor positioning reveal an underlying fragility. The record gold price is a testament to lingering uncertainty.

At the same time, the crypto market’s reaction to Japan’s banking reforms shows how a single, well-targeted policy shift can ignite a new wave of institutional optimism. The critical question moving forward is whether these sector-specific catalysts can withstand a broader macroeconomic shock.

If US equity markets were to extend their losses following a wave of disappointing earnings from the more than 900 firms reporting this week, the pressure on Bitcoin to hold its key US$109,000 support level would be immense. The negative 24-hour correlation of -0.58 between crypto and the Nasdaq suggests that in a true risk-off scenario, the sector-specific bullish narrative from Japan may be quickly overwhelmed by the tide of broader market fear. The next few weeks will be a crucial test of whether the market’s current resilience is a sign of true underlying strength or merely a calm before a more significant storm.


Source: https://e27.co/gold-at-record-highs-crypto-on-a-knifes-edge-contradictions-in-a-risk-on-world-20251021/

Anndy Lian is an early blockchain adopter and experienced serial entrepreneur who is known for his work in the government sector. He is a best selling book author. The latest book is Web4: The Age of Autonomous Intelligence.

j j j