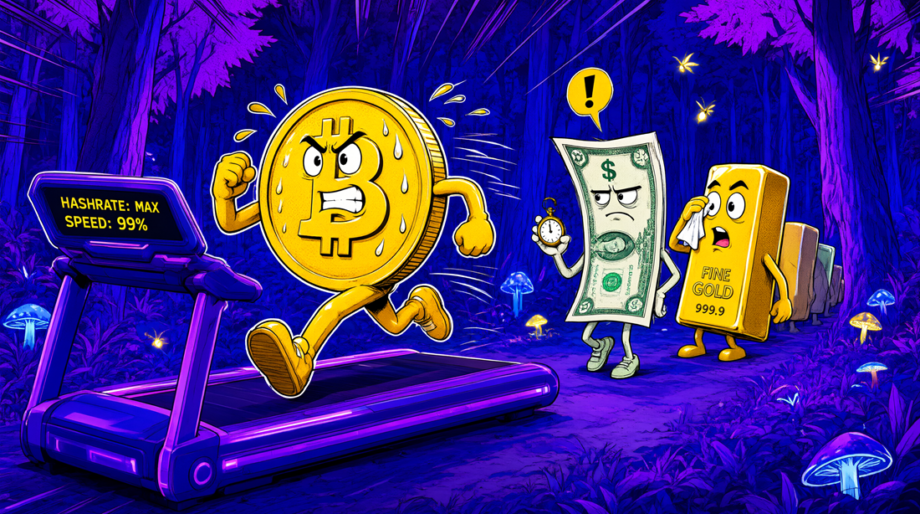
Bitcoin has climbed back above the critical $81,000 baseline. This 24-hour rebound does not erase a difficult month. The digital asset remains in its weakest October performance in 6 years, down roughly 4.2%, while conflicting forces keep price action in a sideways range. The market has spent a long time without a decisive break. That pattern reflects a fierce tug-of-war between strong rebound catalysts and firm upward caps, all against severe macro headwinds and a looming inflation report.
The first support comes from the Federal Reserve. Risk appetite expanded after the central bank voted 10-2 to leave the federal funds target range steady at 3.75% to 4.00%. Avoiding a pre-election liquidity shock triggered an immediate relief rally. Resilient institutional inflows add another layer of stability. Spot US Bitcoin ETFs pulled in $110.34 million in net inflows on October 26, followed by another $176 million on October 27. That steady backing provides a firm price floor.
Several forces actively suppress upward movement. Options traders brace for dramatic swings as a massive $11 billion options expiry closes this Friday. With 70% of dealer hedging sensitivity, known as gamma, concentrated heavily between $75,000 and $82,000, market makers actively suppress large expansions. US demand has turned noticeably soft. The Coinbase Premium Index, which measures the gap between US and offshore spot buying, has not posted 1 positive day all of October and hit its lowest levels since June. Technical resistance failure compounds the issue. On-chain analysts note that Bitcoin recently suffered a clear fakeout near the $83,000 mark. Failure to reclaim and hold this baseline keeps technical day traders on the defensive.
Bitcoin is defying significant macro headwinds. While the Fed paused, Chair Kevin Warsh shifted language to suggest the economy is expanding strongly rather than solidly. At the same time, 2 policymakers dissented in favor of an immediate hike, pushing market odds for a December rate increase up to nearly 75%. Crude oil and yield pressures loom large. Brent crude remains stubbornly elevated at $100 to $111 per barrel amid ongoing Middle East war headlines. This energy shock keeps the 10-year US Treasury yield near a multi-decade high of 5.1% to 5.3%, intensifying competition for non-yielding assets. Midterm election derisking adds another layer. Capital is aggressively de-risking ahead of the November 3 US midterm elections. A highly polarized outlook dictates vast price variances. Institutional consensus projects year-end targets of $90,800 under a unified Republican Congress, versus $76,450 if Democrats sweep both chambers.
The immediate catalyst is the September 2026 Personal Consumption Expenditures price index report, the Federal Reserve’s preferred inflation gauge. Economists project a sharp acceleration in price pressures. The US Bureau of Economic Analysis releases the data at 8:30 AM Eastern Time (8:30 PM Singapore Time). Consensus models anticipate a broad-based monthly and annual tick-up. The September 2026 forecast for the headline PCE price index shows a +0.5% month-over-month increase, up from the +0.3% actual in August. The year-over-year forecast stands at +3.7%, or roughly 3.6%, up from the 3.4% actual in August. Analysts forecast the core PCE price index, which excludes food and energy, to rise +0.3% to 0.32% month-over-month, up from the +0.2% or 0.25% actual in August. Annually, core PCE will likely rise +3.1%, up from the 3.0% actual in August.
Several key drivers explain the expected jump. Higher crude oil and natural gas prices, driven by supply disruptions in the Middle East, pushed energy costs up. Oxford Economics estimates PCE energy prices rose roughly 5.4% in September alone. Persistent core services and goods remain sticky. Following hot Consumer Price Index and Producer Price Index releases earlier in the month, core categories have proven stubborn. Bank of America analysts noted that price pressures span both core goods and core services. Higher input and component costs tied to ongoing corporate artificial intelligence buildouts continue to filter into the computer software, hardware, and accessory sub-indices.
This report drops less than 24 hours after the Federal Open Market Committee voted 10-2 to hold interest rates steady at 3.75% to 4.00%. A hot PCE print confirming headline inflation running at 3.7% and core at 3.1%, well above the Fed’s stubborn 2% target, will validate the 2 dissenting votes for an immediate hike. Interest rate futures have already priced in roughly an 85% to 91% chance of a rate hike by December. An upside surprise in today’s PCE figures could cement expectations that the central bank will resume tightening sooner than risk assets prefer. A hotter-than-expected print will likely lift US Treasury yields, keeping the 10-year near 5.0% or higher, pressure non-yielding assets like Bitcoin and gold, and spark immediate turbulence across equity index futures and the USD/EUR exchange rate.
Global financial markets closed slightly higher after the Federal Reserve split on keeping the benchmark interest rate steady. The S&P 500 rose 0.28% to 7,743.98. The Nasdaq Composite gained 0.27% to 26,549.85. The Dow Jones Industrial Average added 0.19% to 52,475.10. Major US indexes posted their 3rd straight daily gain during regular hours but stayed mostly range-bound. The initial relief rally has given way to sharp divergence and tech-sector volatility in early-morning extended trading as investors closely scrutinize mega-cap AI spending. In early Asian trading and overnight futures, Nasdaq 100 futures have dropped over 1%. The Federal Open Market Committee voted 10-2 to keep interest rates unchanged, as expected. The tone was subtly hawkish. Governor Lisa Cook and Cleveland Fed President Beth Hammack dissented, actively voting for an immediate 25-basis-point hike. The Fed also upgraded its economic assessment to “expanding at a strong pace,” up from “solid,” while noting that inflation remains elevated. Chair Kevin Warsh avoided forward guidance but emphasized readiness to act. The CME FedWatch tool now shows an 85% probability of a December rate hike. Warsh announced an adjusted 2027 calendar, reducing rate-setting votes to 7 of 8 annual meetings.
In my view, Bitcoin sits at a precarious intersection. Resilient institutional inflows and aggressive macro headwinds define the current sideways range. The $81,000 level is a temporary resting point, not a sign of strength. The impending PCE report and the massive options expiry will likely dictate the next leg of volatility. The token has gone too long without a decisive break, and until the Fed pivots or Bitcoin breaks decisively above $83,000, it remains hostage to macro data and derivative positioning. I believe, and I said that yesterday, that the path of least resistance remains downward in the near term, given hawkish Fed rhetoric and technical failures, while the long-term debt-devaluation narrative provides a formidable floor. The September PCE report will serve as the immediate arbiter, determining whether Bitcoin can sustain this rebound or succumb to mounting pressure.
https://e27.co/bitcoin-rebounds-to-us81000-but-faces-weakest-october-in-6-years-20261029/
Anndy Lian is an early blockchain adopter and experienced serial entrepreneur who is known for his work in the government sector. He is a best selling book author. The latest book is Web4: The Age of Autonomous Intelligence.